FIA: Protecting Retirement Money From Bad Timing
How a fixed indexed annuity can act as a protected bucket beside IRA, 401(k), CD, or savings money.
Annuity information · Optional next steps
Personalize Your Retirement Income Review
Explore the information below at your own pace. If you would like to share your income goals, timing and resources, this optional roadmap helps our team understand your questions. Estimates are fine; completing it does not book a call.
One question at a timeAbout 4 minutesReviewed before your callShare what matters to you
Your whole retirement-income picture
Bring your questions about retirement income, available cash, a 401(k), an IRA, brokerage assets or rental income. We can discuss how insurance-based options, including annuities, might fit alongside your existing assets. You do not need to sell a property to have this conversation.
Have a rough picture of your income goals, existing income sources, timing and money that must stay accessible. Costs, taxes, contract restrictions, insurer-backed guarantees and alternatives all matter. Making no change may be the right conclusion.
No account numbers or private document uploads are needed. Property-sale proceeds belong in the discussion only if you are already considering a sale.
Explore Your Annuity Options
Understand Guaranteed Income, FIAs & MYGAs
Use this page to explore guaranteed-income annuities, fixed indexed annuities, MYGAs, income timing, eligible IRA/401(k), TSP and pension funding, liquidity, surrender terms, beneficiaries, and insurer strength. We will compare fit and tradeoffs; no product decision is required.
Questions about these options? Call or text (786) 567-6889.
Whether you asked us for information or already scheduled an annuity conversation, start here. Review the options and bring us your questions.
Meet your teamJared · Ben · Erin
Get to know the team before your call. We can help you compare retirement-income and annuity options, costs, access and tradeoffs.
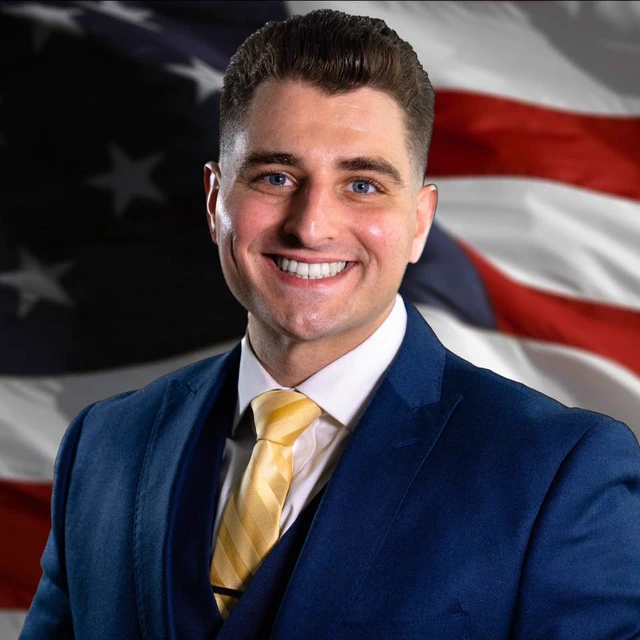
Jared Aversano
Managing Partner
Retirement Income & Annuities
U.S. Air Force veteran · NPN 19759681
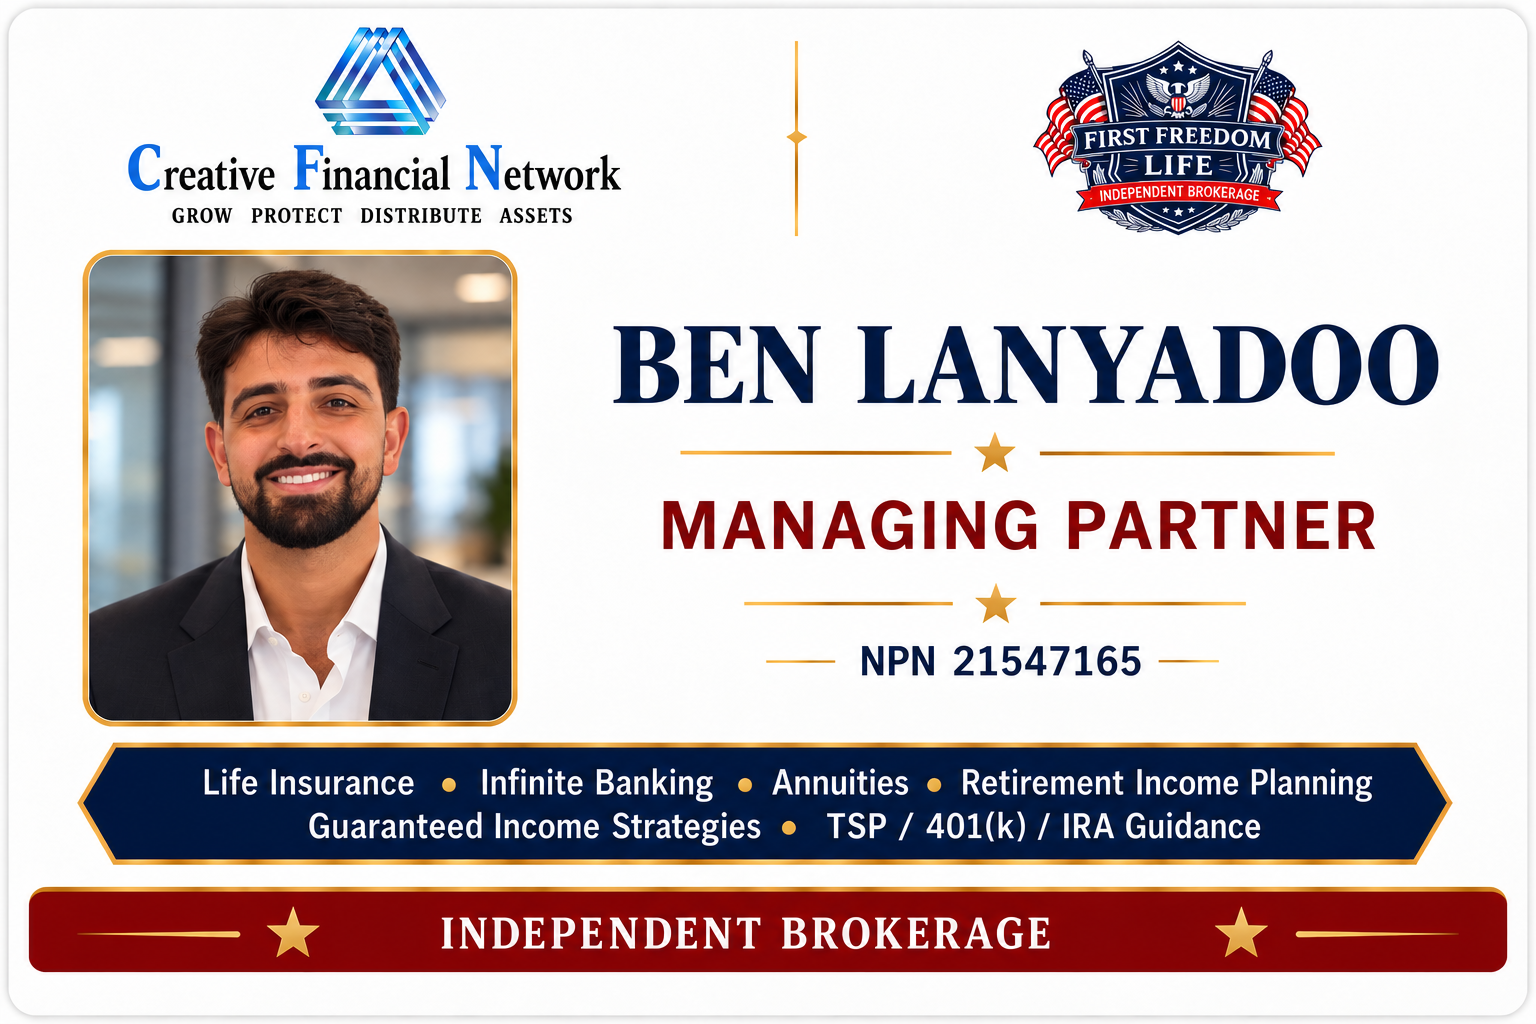
Ben Lanyadoo
Managing Partner
Bachelor’s degree in Legal Studies, UC Berkeley
Retirement Income & Annuities · NPN 21547165
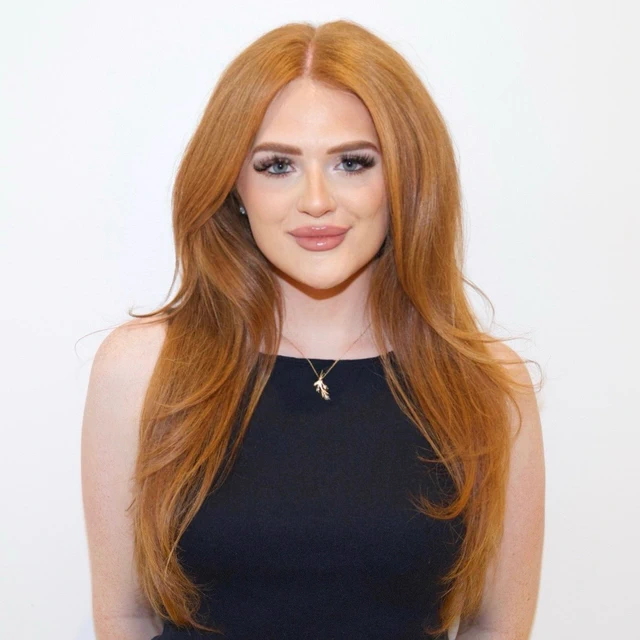
Erin Bovee
Managing Partner
Retirement Income & Annuities
NPN 20292695
First Freedom Life is an independent, veteran-owned insurance brokerage. Product availability and suitability vary; no investment, tax or legal advice is provided.
Start with your goal
Explore the annuity questions that matter to you
Choose a topic to see what it means, what to compare and which questions to bring. You do not need to choose a product.
Explore fixed-rate annuities and MYGAs
A multi-year guaranteed annuity (MYGA) specifies an interest rate for an initial term. It may be worth discussing for money you can leave in place while keeping an accessible reserve elsewhere.
What to compare: Compare the guaranteed term, withdrawal allowance, surrender schedule, any market value adjustment, and the insurer behind the guarantee.
Questions for your conversation
- When might I need access to this money?
- What happens at the end of the guaranteed term?
- How would this compare with a CD or keeping the money accessible?
Understand a fixed indexed annuity (FIA)
An FIA credits interest using a contract formula linked to an index. You do not own the index. Credited interest may be limited by a cap, participation rate or spread, and can be zero.
What to compare: Compare crediting methods, changing strategy terms, fees, withdrawal rules and surrender charges. Protection from direct index losses does not eliminate other contract costs or withdrawal losses.
Questions for your conversation
- How is interest credited, and which terms can change?
- Are there strategy or rider fees?
- What could I receive if I withdraw early?
Compare ways to create retirement income
Immediate or deferred income annuities and some FIAs with income riders can address income needs. The payment start date, single or joint coverage, beneficiary choices and access to money affect the comparison.
What to compare: Compare contractually guaranteed payments, income timing, rider costs and liquidity. An income benefit base used to calculate payments is different from cash you can withdraw.
Questions for your conversation
- When do I want income to begin?
- Should payments cover one life or two?
- What access and beneficiary benefits would I keep or give up?
Keep these questions for a conversation with our team. If you want to share your goals, use the optional Retirement Roadmap.
How we research annuity options
First Freedom Life uses Annuities Genius to research product features, compare income options and review illustrations. We confirm current terms and availability for your situation before discussing a specific contract.
About the comparison tools · Carrier annuity education
Educational guide reviewed October 16, 2026. This guide does not display live rates or provide a personalized quote.
Guarantees depend on the issuing insurer. Fees, surrender charges, withdrawal limits and taxes may apply. Annuities are not FDIC insured. Exploring these topics does not submit a form or book a call.
Retirement & Annuity Videos
Retirement Income, FIA & MYGA Video Guides
Four equal-size explainers on fixed indexed annuities, MYGAs, principal protection, index crediting, liquidity, and retirement-income tradeoffs.
How FIA Index Crediting Actually Works
Caps, spreads, participation rates, and the tradeoff between principal protection and index-linked interest potential.
MYGA vs CD: Locking a Multi-Year Rate
Compare guaranteed annuity rates against CDs, high-yield savings, tax deferral, liquidity, and surrender periods.
Where MYGAs Fit in a Safe-Money Plan
Guaranteed growth, tax deferral, and beneficiary planning for conservative money that does not need full daily liquidity.
Different Annuity Types Solve Different Problems
The goal is not to push “fixed indexed annuities” only. The goal is to match the right contract type to the real job: safe growth, guaranteed income, principal protection, tax deferral, legacy planning, or a 1035 cleanup.
Safe rate
Fixed Annuity
Designed for principal protection and a declared interest rate. Useful when you want predictability and less market drama.
Market-linked upside
Fixed Indexed Annuity
Credits interest based on an index strategy while protecting principal from market losses with a contractual floor.
MYGA
Multi-Year Guaranteed Annuity
Often compared to CDs: a guaranteed rate for a set term, tax-deferred growth, and insurance-company guarantees.
Lifetime income
Income Annuity
Turns a portion of assets into predictable income. Can be structured for immediate or future income needs. Start with the income annuity comparison hub; if a pension offers a choice, review the pension lump sum vs. annuity comparison before deciding.
Cleanup strategy
1035 Exchange
Move an old annuity or life policy into a better-fitting contract without triggering a taxable event when structured correctly.
Compare options
Annuity vs IUL
Annuities and IUL serve different insurance needs. Compare income, life insurance protection, cash-value access, costs and risks. IUL loans and withdrawals can reduce benefits and may have tax consequences.
Three ways to put retirement money to work
Compare MYGA fixed-rate accumulation, FIA indexed accumulation and lifetime-income needs. The video’s 6% example is Oxford Life Multi-Select MYGA: 6.00% annual interest for the initial five-year term, with a $20,000 minimum premium. Other terms and products may differ; five years and $20,000 are not requirements for every review. An FIA’s 0% index-crediting floor does not eliminate fees, surrender charges or withdrawal losses. Checked October 1, 2026. Florida product comparison, subject to eligibility, suitability and availability; rates may change before issue. Early withdrawals may incur surrender charges and a market-value adjustment that can reduce principal. Guarantees depend on Oxford Life Insurance Company’s claims-paying ability. Not FDIC/NCUA insured. Taxes and possible tax penalties are separate. No transfer or product choice is required to request a review.
Income beginning soon
Need income to start within a year?
Read the single premium immediate annuity (SPIA) guide to compare life-only, joint-and-survivor, period-certain, and refund choices alongside liquidity, tax, inflation, and beneficiary tradeoffs.
Independent carrier comparison
Researching Athene annuity options?
Use the independent Athene annuity comparison to review product categories, income choices, liquidity, charges, state availability, and the current-illustration boundary without publishing stale rates or payout figures.
Independent carrier research
Compare annuity carriers without confusing research with a recommendation
These national owner pages are for possible new annuity purchases. They separate carrier and product research from account login, existing-policy service, claims, and securities advice. Current appointment, state availability, approved materials, contract terms, and suitability are confirmed during the review.
Nationwide annuities
Compare fixed, fixed indexed, and immediate categories, including a nonnumeric Peak 10 decision section.
F&G annuities
Review accumulation and retirement-income tradeoffs, including a current-materials boundary for Safe Income Advantage.
Allianz annuities
Compare fixed indexed annuity decisions with distinct sections for the 222+ and Benefit Control product families.
North American annuities
Evaluate fixed indexed retirement-income tradeoffs, including a nonnumeric Income Pay Pro decision section.
Global Atlantic annuities
Separate deferred-income and fixed-annuity research with ForeIncome II and SecureFore II decision sections.
American Equity annuities
Compare fixed indexed accumulation and income designs with IncomeShield and AssetShield product-family context.
Security Benefit annuities
Review fixed and fixed indexed contract tradeoffs, including a nonnumeric Advanced Choice decision section.
Midland National annuities
Compare current insurance-only annuity categories, liquidity, income structure, state availability, and contract terms.
Delaware Life annuities
Review current fixed and fixed indexed annuity choices without relying on stale rates, payout claims, or rankings.
Annuities vs 401(k), IRA, CDs & Savings
This is the comparison people actually make. Retirement accounts are tax wrappers. CDs and savings are bank deposits. FIAs and MYGAs are insurance contracts. The right answer depends on liquidity, tax status, market exposure, rate guarantees, income goals, and surrender-period tolerance.
401(k) / IRATax-advantaged accounts can hold market assets; early distributions before 59½ can trigger IRS penalties unless exceptions apply.
CDs / SavingsFDIC-insured at insured banks up to applicable limits; strongest for liquidity and simplicity, weaker for lifetime-income planning.
FIAFor index-linked interest potential with principal protection from direct market-loss years, subject to contract terms.
MYGAFor a declared multi-year guaranteed annuity rate, tax deferral, and principal protection, subject to insurer strength and surrender rules.
When an annuity may fit
Good fit signals
Retirement assets you want to protect, fear of market losses, need for guaranteed income, old 401(k)/IRA money, a maturing CD, an old annuity with poor terms, or concern about outliving income.
When it may not fit
Not for everyone
If you need every dollar liquid immediately, want full stock-market exposure, or cannot handle surrender periods, an annuity may not be the right tool — or only a small portion may make sense.
Quick Comparison
This is the starting point. The details depend on carrier, age, state, term, riders, income options, liquidity provisions, and tax status.
| Type | Main job | Typical client intent | Watch out for |
|---|---|---|---|
| Fixed Annuity | Guaranteed rate + principal protection | Safe growth without market exposure | Surrender period and liquidity limits |
| Fixed Indexed Annuity | Index-linked interest with downside protection | Upside potential without direct market loss | Caps, spreads, participation rates, rider fees |
| MYGA | Multi-year guaranteed rate | CD alternative / parking retirement assets | Term length, early withdrawal rules |
| Income Annuity | Lifetime or period-certain income | Pension-style retirement paycheck | Inflation, death benefit, liquidity design |
| 1035 Exchange | Move old contract tax-efficiently | Upgrade poor annuity/life contract terms | Do not trigger taxes or restart bad terms blindly |
| Annuity vs IUL | Compare income vs access/legacy | Tax strategy and retirement-income planning | Different tools; neither is automatically better |
Questions After Reviewing This?
Explore the options and note your questions. If you would like help comparing them, call or text First Freedom Life at (786) 567-6889.
Common Annuity Questions
Is this only fixed indexed annuities?
No. Fixed indexed annuities are one category. This page covers fixed, indexed, MYGA, lifetime income, 1035 exchange, and comparison planning.
How do I get help choosing the right annuity type?
Call or text First Freedom Life at (786) 567-6889. The type gets clarified during the conversation: fixed, indexed, MYGA, income, 1035 exchange, or annuity vs IUL.
Are annuities safe?
Some annuities protect principal contractually; others vary. Safety depends on the product type, carrier, guarantees, liquidity terms, and how it fits your plan.
Should I move my 401(k) or IRA?
Maybe, but only after reviewing liquidity, income goals, taxes, fees, surrender periods, beneficiaries, and whether a partial allocation makes more sense.