Watch this first
How Cash Value Life Insurance Works
How permanent life insurance can build usable cash value while keeping protection in place.
Life Insurance You Can Borrow From: IUL vs Whole Life
Life Insurance Quote Form
Start your secure First Freedom Life quote form
Start with the short secure form and choose the time that works best if a scheduling step appears.
Learn how policy loans work in whole life and indexed universal life, including collateral, interest, repayment choices, death-benefit impact, and lapse risk.
Jared + Erin · Founders & Owners
Meet Jared & Erin
Work directly with the veteran-owned founders behind First Freedom Life for Life insurance guidance by phone and video nationwide.
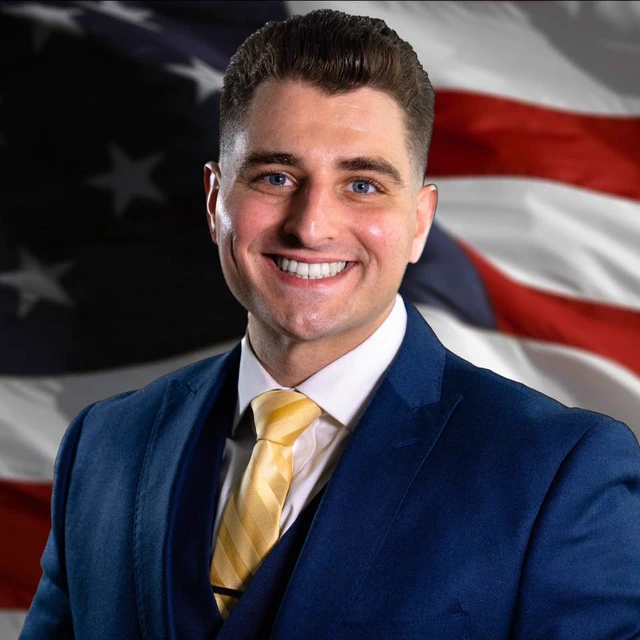
Jared Aversano
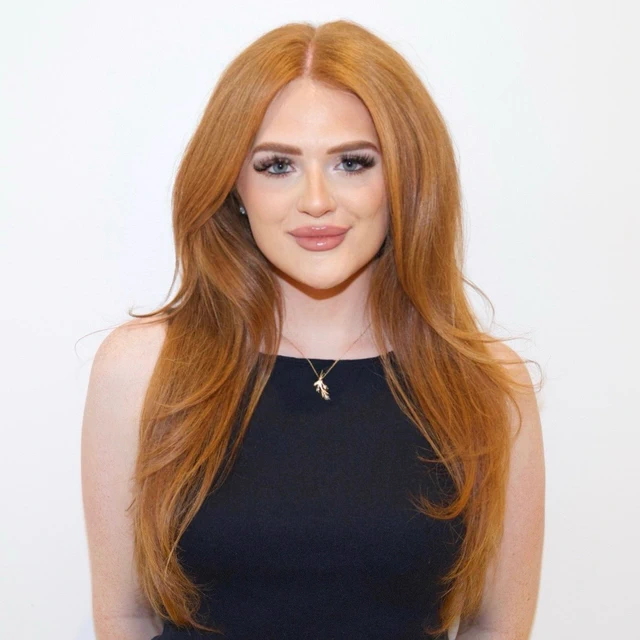
Erin Bovee
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Life Insurance Videos
Life Insurance Video Guides
Short educational explainers on protection, living benefits, cash value, mortgage protection, and veterans coverage.
Using Cash Value Without Losing Control
How policy loans and cash value access are designed to work when a policy is structured correctly.
IUL: 0% Floor, Index Growth, and Life Insurance
A plain-English walkthrough of indexed universal life and why it is not for everyone.
What Makes an IUL Work or Fail
Funding, caps, fees, protection, and why design matters more than hype.
Policy Liquidity: Borrowing Against Cash Value
For qualified policy owners, cash value can become a private liquidity source when the foundation is built correctly.
Cash Value for Qualified Liquidity Planning
Using policy cash value for liquidity, control, and long-term family or business planning without overpromising who qualifies.
Mortgage Protection: Keeping the House Protected
How coverage can help a family stay in the home if income disappears after death or serious illness.
Mortgage Protection vs. Regular Life Insurance
What to know before choosing coverage tied to a mortgage, family income, and living benefits.
Veterans Life Insurance: VGLI vs Private Options
A veteran-focused breakdown of locked-in private coverage, living benefits, and VGLI alternatives.
Veteran-Owned Guidance Before You Decide
What veterans and military families should understand before choosing long-term life insurance.
How a life insurance policy loan works
With a cash-value policy, the insurer generally lends money while the policy's cash value serves as collateral. Interest accrues under the contract. Repayment may be flexible, but an unpaid balance reduces what is available and can reduce the death benefit paid to beneficiaries.
Borrowing too much or allowing charges and interest to outpace the remaining value can cause a policy to lapse. A lapse with an outstanding loan may also create a taxable event, so loans require ongoing monitoring rather than a one-time decision.
Whole life versus indexed universal life
Whole life typically uses a guaranteed cash-value schedule and may pay non-guaranteed dividends. IUL uses flexible-premium universal-life mechanics and index-linked crediting subject to contract terms such as caps, participation rates, spreads, and charges. Loan rates and the treatment of borrowed value vary by carrier and policy.
The better borrowing design cannot be chosen from the product label alone. Compare guaranteed values, current assumptions, surrender periods, premium requirements, direct or participating loan treatment, and performance under conservative stress tests.
Are policy loans tax-free?
Policy loans are generally not treated as taxable income while a qualifying policy remains in force, but that is not an unconditional promise. Modified endowment contract rules, lapse or surrender with gain, and individual circumstances can change the result. A tax professional should confirm the treatment for a specific case.
First Freedom Life approach
First Freedom Life reviews the protection need first, then models access, interest, repayment choices, death-benefit impact, and lapse risk. The aim is to show how the contract behaves before anyone depends on it for liquidity.
Next step
If you want a real comparison instead of generic internet advice, First Freedom Life can review your age, health, budget, goals, and timeline, then show which carriers and policy structures fit. The review is designed to make the decision clear before you apply.