Watch this first
How Cash Value Life Insurance Works
How permanent life insurance can build usable cash value while keeping protection in place.
The 3 Major Tax Benefits of Life Insurance
Life Insurance Quote Form
Start your secure First Freedom Life quote form
Start with the short secure form and choose the time that works best if a scheduling step appears.
Life insurance tax treatment depends on the transaction. Death benefits, cash-value growth, withdrawals, policy loans, surrender, and Modified Endowment Contract (MEC) status can follow different rules.
Jared + Erin · Founders & Owners
Meet Jared & Erin
Work directly with the veteran-owned founders behind First Freedom Life for Life insurance guidance by phone and video nationwide.
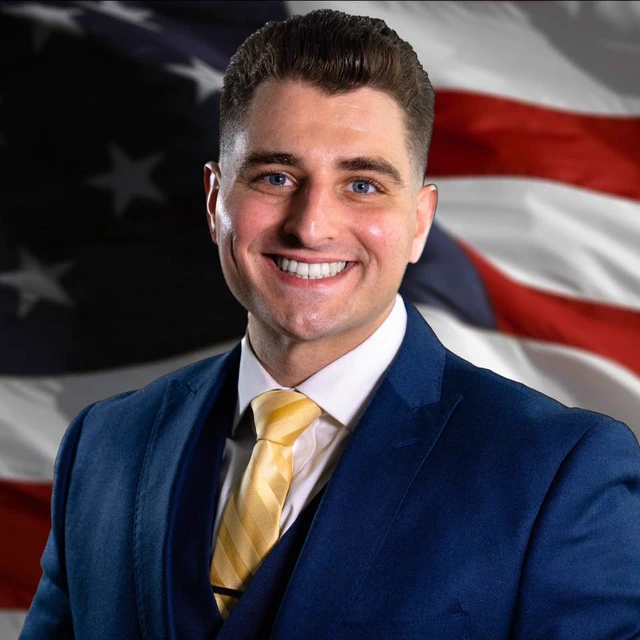
Jared Aversano
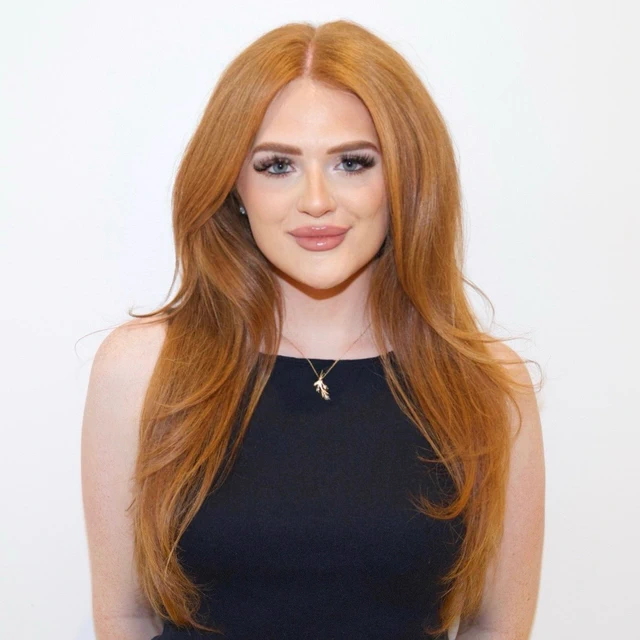
Erin Bovee
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Life Insurance Videos
Life Insurance Video Guides
Short educational explainers on protection, living benefits, cash value, mortgage protection, and veterans coverage.
Using Cash Value Without Losing Control
How policy loans and cash value access are designed to work when a policy is structured correctly.
IUL: 0% Floor, Index Growth, and Life Insurance
A plain-English walkthrough of indexed universal life and why it is not for everyone.
What Makes an IUL Work or Fail
Funding, caps, fees, protection, and why design matters more than hype.
Policy Liquidity: Borrowing Against Cash Value
For qualified policy owners, cash value can become a private liquidity source when the foundation is built correctly.
Cash Value for Qualified Liquidity Planning
Using policy cash value for liquidity, control, and long-term family or business planning without overpromising who qualifies.
Mortgage Protection: Keeping the House Protected
How coverage can help a family stay in the home if income disappears after death or serious illness.
Mortgage Protection vs. Regular Life Insurance
What to know before choosing coverage tied to a mortgage, family income, and living benefits.
Veterans Life Insurance: VGLI vs Private Options
A veteran-focused breakdown of locked-in private coverage, living benefits, and VGLI alternatives.
Veteran-Owned Guidance Before You Decide
What veterans and military families should understand before choosing long-term life insurance.
The three core tax advantages
Three commonly discussed advantages are generally income-tax-free death benefits, tax-deferred cash-value growth, and policy access that may avoid current income tax. They are not one blanket promise: the policy type, transaction, basis, MEC status, and how the contract is maintained all matter.
Tax treatment should not drive someone into the wrong policy. Protection needs, premium capacity, costs, and long-term design come first, and current guidance should be reviewed before a transaction.
Tax-free death benefit
Under current law, death benefits are generally received free of federal income tax. Exceptions and other taxes can apply, including rules involving ownership, estates, transfers for value, and interest paid by an insurer.
Beneficiary designations and ownership should be reviewed regularly with the appropriate legal or tax professional.
Tax-deferred cash value
Cash value inside a permanent life insurance policy generally grows without current annual income tax while it remains in the contract. That is tax deferral, not a promise that every later distribution will be tax-free.
Withdrawals can reduce cash value and death benefits. For a non-MEC policy, withdrawals may be received without current income tax only up to basis; amounts above basis can be taxable. Costs, crediting terms, dividends, and funding still affect policy results.
Policy-loan access
A policy loan is generally not treated as income when taken from a qualifying policy, but it is not free money. Loan interest accrues, and unpaid balances reduce available cash value and death benefits.
A lapse or surrender with a loan outstanding can create taxable income. A full surrender can also produce taxable ordinary income when the amount received exceeds basis. MECs follow different distribution rules, and an additional tax may apply in some situations.
Next step
First Freedom Life can explain policy mechanics and compare carrier illustrations; it does not provide tax advice. Before a withdrawal, loan, surrender, ownership change, or other transaction, confirm the policy details and current law with a qualified tax professional.