Watch this first
How Cash Value Life Insurance Works
How permanent life insurance can build usable cash value while keeping protection in place.
Whole Life vs Term Life Insurance: Which is Right for You?
Cash Value Strategy Quote Form
Start your secure First Freedom Life quote form
Start with the short secure form and choose the time that works best if a scheduling step appears.
Compare whole life vs term life insurance. Understand the cost, cash value, living benefits, and long-term wealth building differences to make the right decision.
Veteran-owned. Independent. More options.
NationwideNorth AmericanAbilityAllianz LifeAmerican Century LifeAmerican EquityAmerican GulfAmerican LifeAmerican NationalAmericoAmeritasAspidaAtheneAtlantic Coast LifeAuguStarAxonicBaltimore LifeBrighthouse FinancialCL LifeCapitol LifeClear SpringCorebridge FinancialDelaware LifeELCO MutualEagle LifeEquiTrustEquitableF&GFarmers LifeGBU Financial LifeGlobal AtlanticGuaranty Income LifeGuardianHeartland NationalISDA LifeIbexisIntegrity LifeJacksonLiberty Bankers LifeLife of the SouthwestLincoln FinancialMassMutualMassMutual AscendMidland NationalMinnesota LifeMutual of OmahaNassauNational Western LifeNew York LifeOceanview LifeOneAmerica FinancialOxford LifePenn MutualPrincipalProtectiveReliance StandardRevol OneRiverSourceSBLISILACSagicorSecurian LifeSecurity BenefitSentinel Security LifeSymetraTalcott FinancialThe StandardThriventTransamericaTruStageUnited LifeWestern Catholic UnionWichita NationalNational Life GroupGerber Life
Life insurance and annuity comparison options. Looking for a company you don’t see? Ask us. Availability varies by state, product and eligibility.
Jared + Erin · Founders & Owners
Meet Jared & Erin
Work directly with the veteran-owned founders behind First Freedom Life for Cash value life insurance guidance by phone and video nationwide.
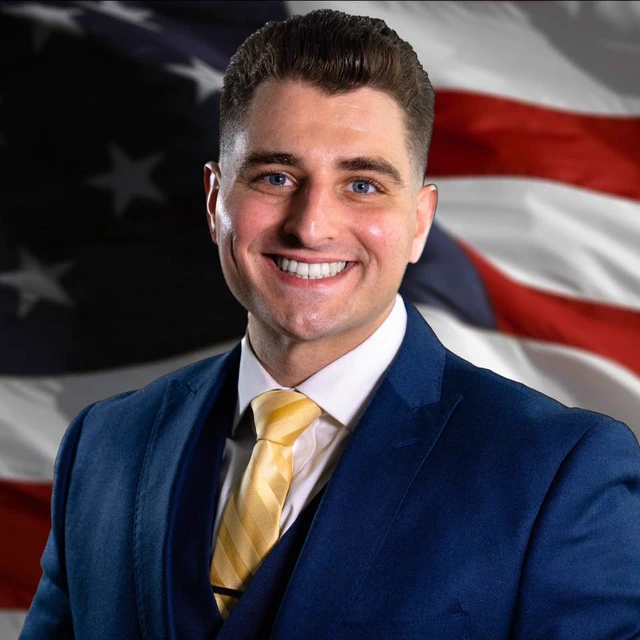
Jared Aversano
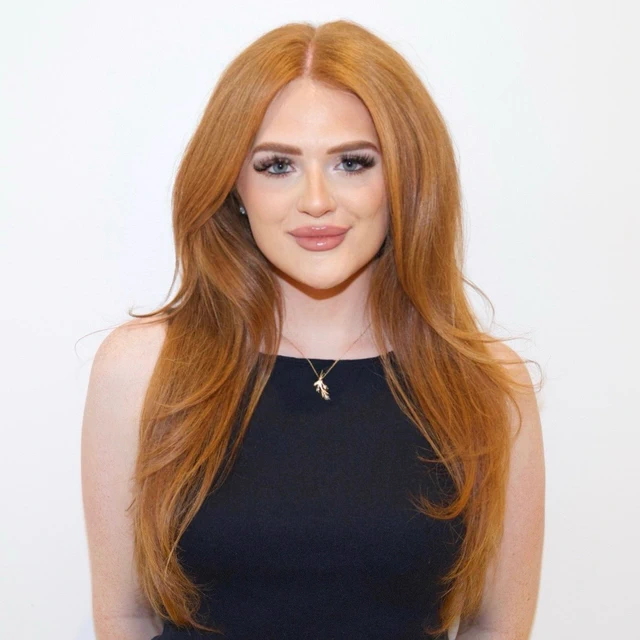
Erin Bovee
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Start with how long the protection is needed
Term life covers a specified period and generally does not build cash value. Whole life is designed for lifelong coverage under its contract, typically with scheduled premiums and guaranteed values when its requirements are met. The first decision is the duration and amount of protection your family needs—not whether a policy has a savings feature.
Compare equal coverage before comparing price
- Temporary need: Income replacement while children are dependent or a mortgage is outstanding may call for substantial coverage over a defined period.
- Long-term need: A continuing dependent, final expenses, or a deliberate legacy objective may justify examining coverage intended to stay in force beyond working years.
- Budget: Compare the same insured person and death benefit. Whole life generally costs more initially than term for similar coverage; avoid leaving a large protection gap to obtain a small cash-value policy.
- Later options: Check term renewal prices, expiration, and any conversion provision before buying. Conversion rights have conditions and deadlines; they are not an unlimited promise.
You can separate temporary and lasting needs
Hypothetical example: a household might need a larger benefit during its working years and a smaller amount for a lasting obligation. Reviewing separate coverage layers may be more useful than forcing all needs into one product. This is a planning example, not a recommended coverage amount or a promise that either policy will be available.
Whole-life cash value is not money you can withdraw without consequences. Loans have interest, and access can affect benefits and policy durability. Dividends on participating policies are not guaranteed. Riders and living benefits must also be compared by their actual eligibility rules, not assumed from the policy label.
Read the NAIC Life Insurance Buyer's Guide and bring both quotes, their premium schedules, and any conversion language to your review. If comparing two permanent options instead, see whole life versus IUL.
Risks and guardrails
Cash-value policies have costs, surrender schedules, and loan interest. If premiums are underfunded or loans are unmanaged, the policy can underperform or lapse. Tax consequences can happen if a policy is mishandled.
That is why policy design, annual reviews, conservative assumptions, and realistic funding are more important than a flashy sales illustration.
How First Freedom Life reviews it
First Freedom Life compares whole life, IUL, and other options through the lens of protection, liquidity, tax treatment, and long-term funding. We explain what the policy can do and what it cannot do.
The right policy should protect the family, fit the budget, and give the owner clear rules for accessing cash value safely.
Next step
If you want a real comparison instead of generic internet advice, First Freedom Life can review your age, health, budget, goals, and timeline, then show which carriers and policy structures fit. The review is designed to make the decision clear before you apply.