🇺🇸 Veteran-Owned & Operated — Proudly Serving American Families | 📞 (786) 567-6889 🇺🇸

Explore IUL Coverage and Cash Value for Your Family.

Start your review

Indexed universal life insurance guidance

Use the secure form to share your name, email, and phone number, then choose a time to speak with First Freedom Life.

Loading your secure form…

Explore indexed universal life insurance for family protection and potential cash value. A personalized illustration helps you compare funding, policy charges, index-crediting limits and living-benefit terms. Illustrated values are not guaranteed.

IUL OptionsCoverage + Cash Value
0% FloorIndex-Crediting Floor
Use While AliveCash Value + Benefits
✅ Free · No obligation ✅ Veteran-owned & licensed ✅ Client Reviews
🇺🇸 Veteran-Owned Multiple A-Rated Carriers

Free. No obligation. Takes 30 seconds to start.

Watch the topic video guides

Veteran-owned. Independent. More options.

NationwideNorth AmericanAbilityAllianz LifeAmerican Century LifeAmerican EquityAmerican GulfAmerican LifeAmerican NationalAmericoAmeritasAspidaAtheneAtlantic Coast LifeAuguStarAxonicBaltimore LifeBrighthouse FinancialCL LifeCapitol LifeClear SpringCorebridge FinancialDelaware LifeELCO MutualEagle LifeEquiTrustEquitableF&GFarmers LifeGBU Financial LifeGlobal AtlanticGuaranty Income LifeGuardianHeartland NationalISDA LifeIbexisIntegrity LifeJacksonLiberty Bankers LifeLife of the SouthwestLincoln FinancialMassMutualMassMutual AscendMidland NationalMinnesota LifeMutual of OmahaNassauNational Western LifeNew York LifeOceanview LifeOneAmerica FinancialOxford LifePenn MutualPrincipalProtectiveReliance StandardRevol OneRiverSourceSBLISILACSagicorSecurian LifeSecurity BenefitSentinel Security LifeSymetraTalcott FinancialThe StandardThriventTransamericaTruStageUnited LifeWestern Catholic UnionWichita NationalNational Life GroupGerber Life

Life insurance and annuity comparison options. Looking for a company you don’t see? Ask us. Availability varies by state, product and eligibility.

Jared Aversano · Veteran-owned

Meet Jared

Work directly with Jared at veteran-owned First Freedom Life for Indexed universal life insurance guidance by phone and video nationwide.

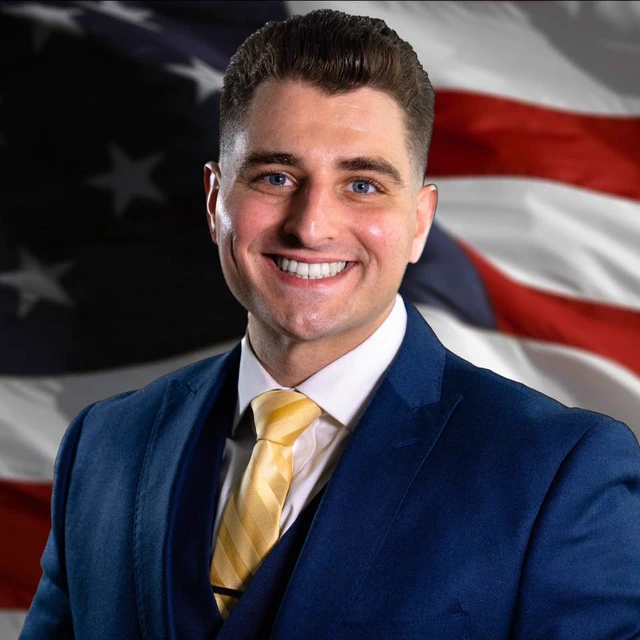
Jared Aversano, U.S. Air Force veteran and owner of First Freedom Life
Owner · U.S. Air Force veteran

Jared Aversano

U.S. Air Force veteran · Indexed universal life insurance guidance · NPN 19759681

First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.

Watch this first IUL: 0% Floor, Index Growth, and Life Insurance A plain-English walkthrough of indexed universal life and why it is not for everyone.

IUL Video

IUL Video Guide

Short explainers on indexed universal life, 0% floors, index-linked growth, policy design, funding, and where IUL can fail if structured poorly.

What Makes an IUL Work or Fail Funding, caps, fees, protection, and why design matters more than hype.
Personalized IUL review

Explore coverage and cash value around your goals.

Your coverage needs, funding capacity and timeline guide the conversation. Discuss a sustainable premium with a licensed professional, then review a personalized illustration and the policy's costs, limits and risks.

1. Share your prioritiesDiscuss family protection, your timeline and funding that fits your circumstances.
2. Compare policy featuresCompare protection, potential cash value and available living-benefit riders, with costs and limits.
3. Get your illustrationA licensed professional explains guaranteed and non-guaranteed illustrated values.
See My IUL Numbers →
✅ No obligation✅ Licensed advisor✅ Personalized illustration✅ Built for families, 1099 earners, and business owners
Who This Is NOT For
❌ People looking to borrow against an existing policy they already own. (We only issue NEW policies). ❌ Those seeking a "get rich quick" scheme or risky stock market investments. ❌ People who are unwilling to review a long-term policy funding plan and its risks.
Who This IS For
✅ Families considering long-term cash value while maintaining life insurance protection. ✅ People comparing a 0% index-crediting floor while understanding that policy charges still apply. ✅ Parents considering life insurance as one part of planning for college, a new home, or future goals.

The Independent Broker Advantage

We are not captive to any single insurance company. We work for you.

🏢

Unbiased Strategy

Captive agents generally represent one insurer. As an independent brokerage, we can compare available policies from multiple insurers for fit, costs, guarantees, illustrated values, and underwriting.

🔍

Multiple Carrier Options

We compare available policies for your profile, including funding requirements, costs, contractual guarantees, illustrated values, and living-benefit terms. Results and eligibility vary by policy and insurer.

🎯

Custom-Tailored Fit

There is no one-size-fits-all policy. We review your health, budget, coverage needs, and goals to compare available carrier and policy options for your situation.

Your Free IUL Strategy Session Includes

Everything you need to make an informed decision about an IUL — at no cost.

✓
Personalized IUL Illustration

See projected cash value growth over 10, 20, and 30 years based on your age, health, and funding level. Compare multiple carriers side by side.

✓
Max Funded IUL Analysis

See how funding near non-MEC limits affects projected cash value and death benefit under guaranteed and current assumptions.

✓
Living Benefits Breakdown

Review what critical, chronic, and terminal illness riders cover, including eligibility triggers, benefit limits, and tax questions to discuss with qualified professionals.

✓
IUL vs. 401(k) vs. Whole Life Comparison

Clear analysis showing how an IUL stacks up against your current retirement strategy — with real numbers.

✓
Zero Pressure. Zero Obligation.

We educate first. If an IUL isn't the right fit, we'll tell you — and you'll walk away smarter than before.

Ready to See Your Numbers?

Get a personalized IUL illustration showing your projected cash value growth — free, no obligation.

Build My Max Funded IUL Plan →
✅ Takes 30 seconds ✅ Exam requirements vary ✅ Compare available policy options

IUL (Indexed Universal Life) Insurance FAQ

What is an IUL?

An IUL — indexed universal life insurance — is permanent life insurance whose interest credits can be linked to an index such as the S&P 500, subject to caps, participation rates, spreads, and a 0% floor. The policy is not directly invested in the index, and policy charges still apply. It also provides a death benefit and may offer living benefits.

How does IUL cash value work?

The 0% floor applies to index-crediting before policy charges; it is not a guarantee that the policy or cash value cannot decline. Cash value depends on premiums, credited interest, charges, withdrawals or loans, and lapse risk. Access may be available through withdrawals or policy loans, which can reduce cash value and the death benefit and can create tax consequences if the policy lapses.

Is IUL good for retirement?

An IUL can supplement retirement planning when permanent death-benefit protection is also needed and the policy can be funded consistently. It is not automatically better than a 401(k), IRA, or other retirement account. Compare guarantees, non-guaranteed assumptions, charges, loan terms, lapse risk, and the effect of withdrawals before deciding.

What is a max funded IUL?

A max-funded IUL is designed to place as much premium as allowed into cash value while using the minimum death benefit permitted by tax rules and carrier design. Funding must stay below modified endowment contract (MEC) limits when non-MEC treatment is intended. MEC limits, policy charges, funding capacity, and ongoing monitoring matter; max-funded does not mean guaranteed maximum returns.

What should an IUL illustration show?

Request guaranteed and current or non-guaranteed columns, plus premium outlay, policy charges, cash and surrender value, death benefit, and loan scenarios at year 10, 20, and 30. Test lower crediting assumptions and possible cap or participation-rate changes. An illustration is not a guarantee of future policy performance.

How is IUL different from whole life?

Both are permanent life insurance. Whole life has contractually guaranteed values and may pay non-guaranteed dividends. IUL uses non-guaranteed indexed interest crediting subject to caps, participation rates, spreads, a floor, and policy charges. The better fit depends on the protection need, guarantees, flexibility, funding plan, and risk tolerance.

Is IUL better than a 401(k)?

IUL and a 401(k) serve different purposes and are not substitutes. A 401(k) is a retirement investment account governed by contribution, employer-plan, and tax rules; an IUL is a life insurance contract with insurance charges and non-guaranteed cash-value performance. Compare protection needs, costs, liquidity, guarantees, taxes, and investment alternatives with qualified professionals.

How much does an IUL cost?

IUL cost depends on age, health, death benefit, carrier, riders, and funding design. A $300-per-month design can be illustrated, but whether it is adequate depends on the insured and the policy's charges and limits. A personalized illustration should separate guaranteed from non-guaranteed values and show the planned premium, surrender value, and lapse sensitivity.

Why First Freedom Life for my IUL?

First Freedom Life is an independent, veteran-owned life insurance brokerage. We compare available IUL policies for your coverage need, budget, underwriting profile, costs, guarantees, illustrated values, and rider terms. Availability, eligibility, and suitability vary by insurer, policy, and individual circumstances.
Comprehensive Guide to Indexed Universal Life Insurance (IUL)

Indexed Universal Life Insurance (IUL) is permanent life insurance designed for death-benefit protection with potential cash-value accumulation. Interest credits may be linked to an index such as the S&P 500, but the policy is not directly invested in the market. Crediting terms, policy charges, funding, withdrawals, loans, and lapse risk all affect results, so an IUL should be evaluated against the protection need and other planning alternatives.

How the 0% Crediting Floor and Caps Work

A 0% floor generally means negative index performance produces no indexed interest credit for that segment before policy charges. It does not prevent policy values from declining because charges, loans, withdrawals, and insufficient funding still matter. Positive index credits can be limited by caps, participation rates, or spreads. Compare guaranteed and current illustrations and test lower assumptions rather than treating the floor as a performance guarantee.

Tax Treatment and IRS Section 7702

Cash-value growth is generally tax-deferred while a life insurance contract qualifies under applicable tax rules. Withdrawals up to basis and properly managed policy loans may avoid current income tax, but loans accrue interest, reduce available value and death benefit, and increase lapse risk. A policy lapse or surrender with a gain can create taxable income, and modified endowment contract (MEC) status changes distribution treatment. Policyholders should review their design with licensed insurance and qualified tax professionals.

Living Benefits: Protection While You Are Alive

Some IUL policies offer accelerated living-benefit riders for qualifying terminal, chronic, or critical illness events. Availability, definitions, waiting periods, benefit amounts, costs, and tax treatment vary by carrier, rider, state, and individual circumstances. Rider benefits can reduce the remaining death benefit and should be reviewed in the policy contract.

Privacy Policy Terms of Service
© 2026 First Freedom Life. All rights reserved.
🛡️ Book IUL Review
💬 Text Us 📞 Call Now
📞 Call Now (786) 567-6889 💬 Text Us 🛡️ Book →
Veteran-owned independent life insurance agency helping families nationwide Client Reviews Call (786) 567-6889