Watch this first
FIA: Protecting Retirement Money From Bad Timing
How a fixed indexed annuity can act as a protected bucket beside IRA, 401(k), CD, or savings money.
Guaranteed Retirement Income in Alabama
One secure review
Schedule a Guaranteed Retirement Income conversation
Choose a time below. We will start with your goals, current resources or protection, time horizon, liquidity needs, health or qualification details when relevant, and the tradeoffs you want explained.
This is the only form on this page. No application or purchase occurs by scheduling.
Alabama statewide guide · Distribute retirement assets as dependable income.
Compare insurance-based income choices around start date, payout duration, single or joint life, liquidity, beneficiary provisions, and the portion of savings used. First Freedom Life is a Florida-based veteran-owned independent insurance brokerage serving Alabama by phone and video.
Schedule My Appointment →Founders & Owners: Jared + ErinIndependent BrokerageStatewide Remote Service
Jared + Erin · Founders & Owners
Meet Jared & Erin
Work directly with the veteran-owned founders behind First Freedom Life for Annuity income guidance by phone and video nationwide.
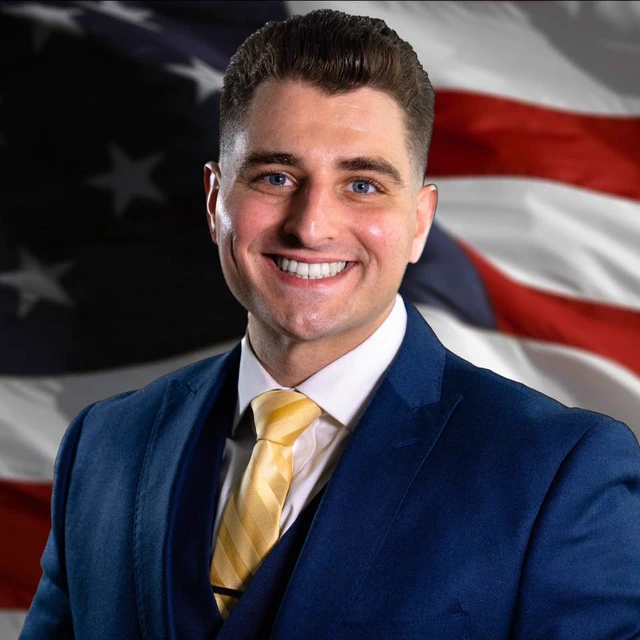
Jared Aversano
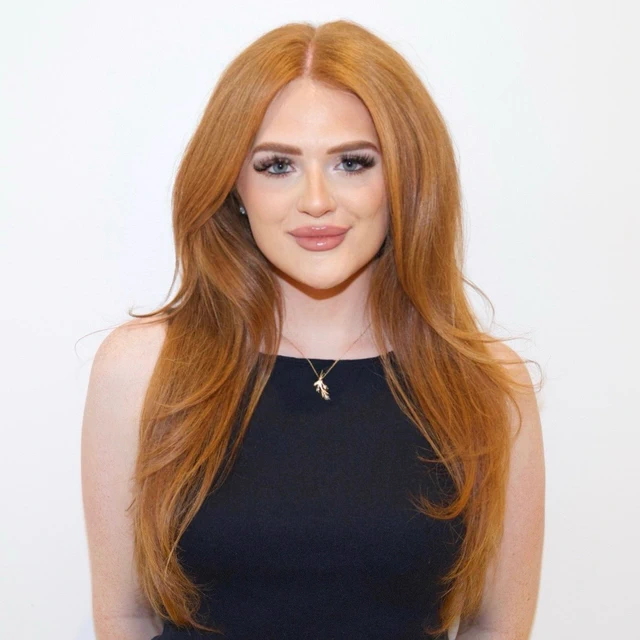
Erin Bovee
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Retirement Income Video Guide
Guaranteed Retirement Income Video for Alabama, AL
Short explainers on protected retirement money, income planning, index crediting, contract tradeoffs, and why liquidity and suitability come first.
How FIA Index Crediting Actually Works
Caps, spreads, participation rates, and the tradeoff between principal protection and index-linked interest potential.
Grow · Protect · Distribute
A decision based on your goals
Distribute retirement assets as dependable income. The review starts with what the money or protection must accomplish, then compares suitable contract options and tradeoffs.
- Income gap and start date
- Single-life or joint-life needs
- Lifetime or period-certain choices
- Liquidity and emergency reserves
- Beneficiary provisions and insurer strength
Alabama insurance context
Alabama Department of Insurance
The Alabama Department of Insurance is the official jurisdiction identity listed by the NAIC for Alabama. Use its current consumer resources to verify producer licensing, locate complaint guidance, and confirm state notices before relying on any summary.
For guaranteed retirement income, review the issued contract and current AL requirements for approved forms, replacements, disclosures, suitability or best-interest duties where applicable, and consumer protections.
Official state verification pathNAIC insurance department directory · Alabama · department ID 1025
First Freedom Life does not provide tax, legal, or investment advice.
Statewide coverage
Guaranteed Retirement Income throughout Alabama
Statewide service includes 576 listed communities in Alabama, including Abbeville, Abernant, Adamsville, Addison, Adger, Akron, Alabaster, Alberta. This coverage list describes remote service availability and does not claim a local First Freedom Life office in each community.
Plain-English answers
Alabama questions
Must every retirement dollar be placed into an annuity?
No. A review can consider only the portion appropriate for dependable income while preserving liquidity and other investments for separate goals.
Can qualified retirement money fund an annuity?
Eligible funds may be transferable or rollable depending on the account and transaction. Coordinate tax and plan-specific questions with the custodian, administrator, and tax professional.
How is guaranteed retirement income regulated in Alabama?
Insurance products, producer licensing, approved forms, replacement requirements, consumer protections, and complaint processes are governed at the state level. Product availability and exact requirements vary; verify current information with the Alabama Department of Insurance and the issued contract.
2024 ACS statewide planning context
Income-planning context for retirement in Alabama
The ACS estimates 904,259 residents age 65 or older, 1,997,247 households, and 3,939,885 civilian adults in Alabama. Population data cannot determine an income plan. A dependable-income review starts with the actual income gap, desired start date, single- or joint-life need, liquidity, beneficiary provisions, inflation concerns, existing assets, and insurer strength.
Residents age 65 and older
904,259
± 5,988 margin of error
Households
1,997,247
± 6,490 margin of error
Civilian residents age 18 and older
3,939,885
± 1,037 margin of error
Official source and scopeU.S. Census Bureau · 2024 ACS 5-year Detailed Tables · B01001, B11001, B21001 · Alabama (0400000US01) · margins of error shown at 90% confidence. Statewide estimates do not describe an individual applicant, contract, rate, or outcome.
Dependable-income design questions for Alabama
A retirement-income plan must define the actual income gap, start date, single- or joint-life need, liquidity held outside the contract, surrender limits, beneficiary choices, inflation concerns, rider costs, and the issuing insurer’s claims-paying ability. Local demographic context never determines suitability or promises an outcome.
Product availability, features, guarantees, costs, liquidity, surrender terms, taxation, underwriting, and suitability vary. Guarantees depend on the issuing insurer's claims-paying ability and contract terms. First Freedom Life is not affiliated with any government agency.