🇺🇸 VETERAN-OWNED & OPERATED  |  A-RATED CARRIERS  |  Client Reviews  |  FREE QUOTE: (786) 567-6889

Build Retirement Income & Cash Value Around Your Goals in California

Free Annuity Income & Infinite Banking Review

Start your strategy review

Use the short secure form to tell us what you want to solve. The calendar remains our general First Freedom Life review.

Build, protect and use your wealth with a strategy shaped around your goals. We help people in California explore guaranteed retirement income through annuity contracts and long-term cash value through suitable Infinite Banking and life-insurance strategies. Your First Freedom Life review starts with your goals, funding and liquidity needs—not a required product. Meet with our independent, veteran-owned team by phone or video.

Retirement incomeGuaranteed Income AnnuitiesBuild an income plan around when you want payments to begin, how long you need them, and the money you want to keep accessible.
Cash-value strategyInfinite BankingExplore a properly designed whole life policy for long-term cash value and policy loans, with a funding plan that fits your goals.

Also here for life insurance, mortgage protection, IUL and other coverage needs. Start with your goals—not a required product.

Annuity guarantees depend on the issuing insurer and contract. Policy loans charge interest and reduce available value and death benefits; costs, liquidity and eligibility vary.

🇺🇸 Veteran-Owned & Operated Client Reviews A.M. Best 'A' to 'A+' Rated Carriers

Free. No obligation. Takes less than 2 minutes.

Jared + Erin · Founders & Owners

Meet Jared & Erin

Work directly with the veteran-owned founders behind First Freedom Life for Annuity income + Infinite Banking guidance by phone and video nationwide.

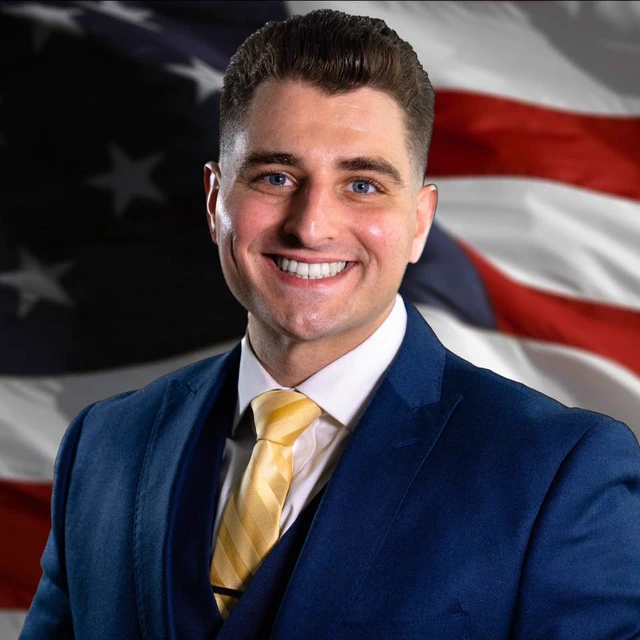
Jared Aversano, co-founder and owner of First Freedom Life
Co-Founder & Owner

Jared Aversano

U.S. Air Force veteran · Annuity income + Infinite Banking guidance · NPN 19759681

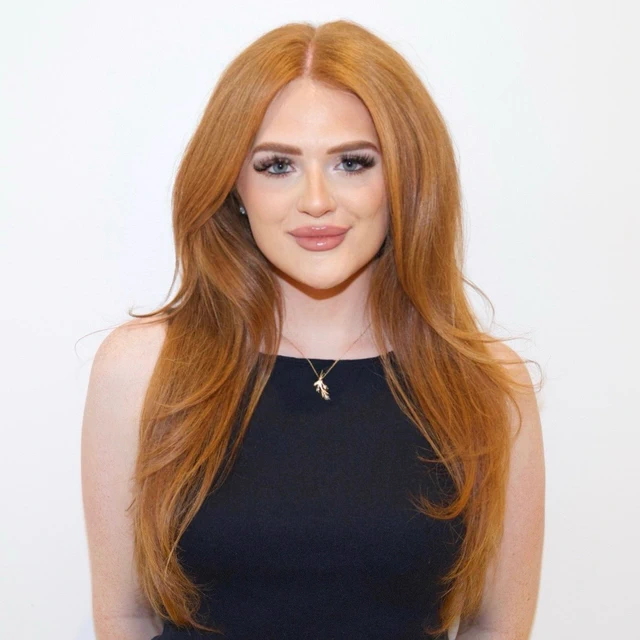
Erin Bovee, co-founder and owner of First Freedom Life
Co-Founder & Owner

Erin Bovee

Annuity income + Infinite Banking guidance · NPN 20292695

First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.

Every First Freedom Life video guide

FIA, Infinite Banking, MYGA & Life Insurance Videos

FIA and retirement-income education comes first, followed immediately by cash-value, IUL, and Infinite Banking education. Mortgage-protection and veterans videos remain visible in the same equal-card library.

Start here · retirement income FIA: Protecting Retirement Money From Bad Timing How a fixed indexed annuity can act as a protected bucket beside IRA, 401(k), CD, or savings money.
How FIA Index Crediting Actually Works Caps, spreads, participation rates, and the tradeoff between principal protection and index-linked interest potential.
MYGA vs CD: Locking a Multi-Year Rate Compare guaranteed annuity rates against CDs, high-yield savings, tax deferral, liquidity, and surrender periods.
Where MYGAs Fit in a Safe-Money Plan Contract-defined interest, tax deferral, liquidity limits, and beneficiary planning for conservative money that does not need full daily access.
Using Cash Value Without Losing Control How policy loans and cash value access are designed to work when a policy is structured correctly.
IUL: 0% Floor, Index Growth, and Life Insurance A plain-English walkthrough of indexed universal life and why it is not for everyone.
What Makes an IUL Work or Fail Funding, caps, fees, protection, and why design matters more than hype.
Policy Liquidity: Borrowing Against Cash Value For qualified policy owners, cash value can become a private liquidity source when the foundation is built correctly.
Cash Value for Qualified Liquidity Planning Using policy cash value for liquidity, control, and long-term family or business planning without overpromising who qualifies.
How Cash Value Life Insurance Works How permanent life insurance can build usable cash value while keeping protection in place.
Mortgage Protection vs. Regular Life Insurance What to know before choosing coverage tied to a mortgage, family income, and living benefits.
Veterans Life Insurance: VGLI vs Private Options A veteran-focused breakdown of locked-in private coverage, living benefits, and VGLI alternatives.
Veteran-Owned Guidance Before You Decide What veterans and military families should understand before choosing long-term life insurance.
Mortgage Protection: Keeping the House Protected How coverage can help a family stay in the home if income disappears after death or serious illness.

The Trifecta Strategy: 3 Benefits in 1 Policy

Some permanent policies combine a death benefit, living-benefit riders, and tax-deferred cash value. Availability, charges, funding needs, and tax treatment depend on the policy and how it is used.

01 — Protection

Tax-Free Death Benefit

Your family gets a tax-free payout if something happens to you. Income replaced. Debts covered. Security guaranteed.

  • Income replacement for your family
  • Mortgage and debt coverage
  • Tax-free payout to beneficiaries
  • Permanent — never expires
02 — Access

Living Benefits

If you're diagnosed with a critical, chronic, or terminal illness, you can access your death benefit while you're alive. No extra cost with most carriers.

  • Heart attack, stroke, cancer
  • Chronic illness — can't perform daily activities
  • Terminal diagnosis — immediate access
  • Tax-free. Use for anything.
03 — Wealth

Tax-Deferred Cash Value

Cash value generally grows tax-deferred. Loans use available policy value as collateral and accrue interest. Non-MEC policy loans generally avoid an immediate federal income-tax event, but lapse or surrender with unpaid debt can create taxable income. Review policy charges, access limits, and the effect on the death benefit.

  • Tax-deferred compounding growth
  • Loan tax treatment depends on MEC status and keeping the policy in force
  • 0% index-crediting floor, subject to policy terms and charges
  • Your money works for you, not a bank

Indexed Universal Life (IUL): How Your Cash Value Grows

An IUL is the engine behind the Trifecta for many of our clients. Here's how it works in plain English.

Growth Mechanism

Market-Linked, Not Market-Invested

Your cash value earns interest based on how a market index (like the S&P 500) performs. But you're NOT in the stock market. The insurance carrier credits your account based on index movement.

  • When the index rises → credited interest depends on the contract limits and charges
  • When the index falls → a 0% crediting floor can apply, but charges may reduce net policy value
  • Credited interest follows the contract; charges, loans, and withdrawals can reduce policy value
  • Growth is tax-deferred inside the policy
What to Compare in an Illustration:

Request an illustration for your actual age, health, premium budget, and coverage need. Compare guaranteed and non-guaranteed values, charges, and available loans under lower-crediting assumptions. An illustration is not a forecast or a guaranteed income stream.

Policy-Loan Access

Borrow Against Available Cash Surrender Value

When sufficient cash surrender value is available, a policy loan may fund different needs. Loan interest accrues and policy terms limit access. Tax treatment depends on MEC status; lapse or surrender with unpaid debt can create taxable income.

  • Non-MEC loans generally avoid immediate income tax; lapse or surrender can trigger tax
  • Access depends on available loan value and insurer procedures
  • Values and crediting while borrowed depend on the policy and loan terms
  • Plan repayments with loan interest and policy funding needs in mind

Infinite Banking: The Rockefeller Method

The wealthy have used life insurance as a banking system for over 100 years. Here's why — and how you can too.

The Concept

Become Your Own Bank

With a properly structured cash value life insurance policy, you may be able to borrow against available policy value. Loan interest is charged by the insurer, and unpaid loans can reduce policy values and the death benefit.

  • Fund a properly structured cash value policy
  • Borrow against it whenever you need capital
  • Repay the insurer loan; interest is charged by the insurer
  • Compare policy credits or dividends with loan costs; positive net growth is not guaranteed
Why It Works

Compare the Full Cost of Borrowing

Policy loans can provide flexible access to available cash value without a traditional bank approval process. Loan terms, interest, policy charges, and the risk of lapse should be reviewed before borrowing.

  • Compare a policy loan with other financing costs before borrowing
  • Fund business expenses with your own capital
  • Cover emergencies without touching retirement
  • Build generational wealth that passes tax-free

What Is Infinite Banking?

A proven wealth strategy used by families, entrepreneurs, and corporations for over 100 years.

Infinite banking is a financial strategy where you use a specially designed cash value life insurance policy as your own personal banking system. The concept was formalized by Nelson Nash in his book Becoming Your Own Banker (2000), though the underlying principles — using whole life insurance as a capital reserve and lending system — have been employed by wealthy families like the Rockefellers for generations.

Infinite Banking traditionally uses participating whole life insurance; an IUL policy has different crediting and cost mechanics. Loans use available policy value as collateral and accrue interest payable to the insurer. Policy value follows the contract while a loan is outstanding; dividends or credits are not guaranteed to exceed loan costs. Unpaid debt reduces available value and the benefit paid at death, and lapse or surrender can cause a taxable event.

A whole life design may use paid-up additions (PUA) riders, subject to contract limits and MEC testing. There is no universal funding level or year when useful cash value appears. An actual illustration should show required and optional premiums, early cash surrender value, charges, and loan terms. Flexible repayment does not remove loan interest or the need to keep the policy in force.

Cash value generally grows tax-deferred. Loans from a policy that is not a Modified Endowment Contract (MEC) generally do not create an immediate federal income-tax event, but lapse or surrender with debt can create taxable income. Death benefits are generally received free of federal income tax, subject to exceptions. Living benefits have separate eligibility, policy, and tax conditions. Review these features together with the costs and protection need.

Want to learn more? Read our complete guide to infinite banking, or explore the Rockefeller Method to see how the wealthiest families in history used these same principles.

Living Benefits: What They Actually Cover

This is the benefit that surprises most people. Your life insurance can pay you while you're alive.

Critical Illness

🫀 Immediate Access

A qualifying critical illness triggers a tax-free lump-sum payment from your death benefit.

  • Heart attack
  • Stroke
  • Invasive cancer
  • Major organ transplant
  • Coronary artery bypass
Chronic Illness

🏥 Ongoing Support

If you can no longer perform daily living activities or have severe cognitive impairment, your policy steps in.

  • Can't perform 2 of 6 daily activities
  • Severe cognitive impairment
  • Annual benefit access
  • Use funds for anything you need
Terminal Illness

🛡️ Immediate Relief

A terminal diagnosis (12-24 months) unlocks a significant portion of your death benefit immediately.

  • Lump-sum access while alive
  • Cover medical costs
  • Create lasting memories
  • No extra premium with most carriers

Living benefit riders are included at no extra cost with most carriers we work with. Details vary by carrier and state.

Whole Life vs. IUL — We Offer Both

The right tool depends on your goals. We'll help you determine which fits best for your situation.

FeatureWhole LifeIUL
GrowthGuaranteed, steadyMarket-linked, higher ceiling
Downside protectionGuaranteed growth0% floor
PremiumFixedFlexible
Death benefitFixedAdjustable
Best forConservative, guaranteedGrowth-oriented, flexible

Both are permanent life insurance options that can build cash value when properly funded. Guarantees, charges, and policy risks differ, so the right fit depends on your needs and the contract terms.

Questions You're Probably Thinking

We get it. This sounds different from what you've been told. Let's address the elephant in the room.

"Is this a scam?"

No. First Freedom Life is a licensed, veteran-owned insurance brokerage. Every carrier we work with — National Life Group, Nationwide, Mutual of Omaha, and others — is A-rated and regulated by state insurance departments. We're backed by AmeriLife, one of the largest insurance distribution companies in America. Your money goes to the insurance carrier, not to us.

"Is this too good to be true?"

It sounds that way because most people have never been taught about these strategies. Cash value life insurance, infinite banking, and tax-free policy loans aren't new — they've existed for over 100 years. The Rockefellers, Walt Disney, and J.C. Penney all used them. Banks use them right now on their own balance sheets. The information just hasn't been widely shared — because Wall Street and banks don't profit when you use these tools.

"Why haven't I heard of this?"

Because the people who profit from the traditional financial system — banks, Wall Street firms, 401(k) managers — don't make money when you put your wealth into a life insurance policy. Your financial advisor gets commissions on mutual funds and 401(k) plans. They have zero incentive to tell you about a strategy that moves your money out of their control. But the wealthy have always known.

"What's the catch?"

The honest answer: these policies work best when they're properly structured and held long-term (10+ years for maximum cash value). They're not get-rich-quick schemes. They're wealth-building tools that compound over time. If you need immediate liquidity or are looking for short-term gains, this isn't the right fit — and we'll tell you that upfront. We only recommend strategies that genuinely serve you.

Who Uses These Strategies?

If any of these describe you, this strategy could change your financial future.

👨‍👩‍👧‍👦

Families Who Want Real Protection

You have people who depend on you. You want coverage that protects them if you die AND helps you if you get sick.

🏗️

Hard-Working Professionals

Truck drivers, tradespeople, and blue-collar workers who carry real physical risk and deserve real financial tools.

💼

Business Owners & Entrepreneurs

You want to build wealth on your terms, reduce tax exposure, and create a financial system you control — not the bank.

🏦

People Interested in Infinite Banking

You've heard about becoming your own bank or the Rockefeller Method and want to learn how it actually works.

Partnered Exclusively with A.M. Best 'A' to 'A+' Rated Carriers

As an independent brokerage, we shop multiple A.M. Best Excellent and Superior rated carriers to find the best fit for your goals — not just one company's product.

National Life Group Nationwide Mutual of Omaha Transamerica OneAmerica F&G North American Protective + More

★ Frequently Asked Questions ★

What is Infinite Banking?

Infinite Banking uses cash value life insurance, traditionally participating whole life, as one way to plan access to capital. Early accessible value may be limited. Premium commitments, policy charges, loan interest, non-guaranteed dividends, and lapse risk must be compared with other ways to save or borrow.

What is an IUL (Indexed Universal Life) policy?

Indexed Universal Life (IUL) is permanent life insurance with interest crediting linked in part to an index. A 0% index-crediting floor does not prevent policy charges, loan interest, or withdrawals from reducing net policy value. Caps, participation rates, and other terms limit credits. Cash value grows tax-deferred; loan tax treatment depends on MEC status and keeping the policy in force.

Can I access my money without penalties?

Policy loans generally do not create an immediate federal income-tax event when the policy is not a Modified Endowment Contract (MEC). Available value, loan interest, and policy terms limit access. A lapse or surrender with a loan outstanding can create taxable income; unpaid loans reduce the benefit paid at death.

How is this different from regular life insurance?

Term insurance provides coverage for a set period and some term policies offer living-benefit riders. Permanent policies may also build tax-deferred cash value. Compare costs, coverage needs, rider eligibility, and funding commitments before choosing.

What are living benefits?

Living benefits let you access a portion of your own death benefit while you're still alive if you're diagnosed with a critical illness (like cancer or heart attack), chronic illness, or terminal illness. The insurance company advances you tax-free cash — you can use it for medical bills, mortgage payments, or lost income. Most carriers include this at no extra cost.

Who is this for?

Suitability depends on a protection need, an affordable premium commitment, time horizon, liquidity needs, and the policy terms. Income alone does not determine whether a cash value strategy is appropriate.

How are living benefits different from health insurance?

Health insurance pays hospitals and doctors directly. Living benefits pay YOU — a tax-free lump sum deposited straight to your bank account. You can use it for anything: medical bills, your mortgage, lost income, or whatever your family needs most.

Do I need good credit?

No. Life insurance policy loans don't require credit checks. Your policy is the collateral.

How is infinite banking different from a savings account?

A savings account and cash value life insurance serve different purposes. Life insurance has underwriting, premiums, policy charges, and loan interest; early cash surrender value may be limited. Policy values follow the contract while a loan is outstanding, and dividends or credited interest may be affected by the loan terms. Cash value grows tax-deferred, and lapse or surrender can create a taxable event.

Does infinite banking really work?

Yes — when implemented correctly. The Infinite Banking Concept was introduced by Nelson Nash and has been used successfully for decades. The key is a properly designed policy that maximizes cash value growth, not commissions. Wealthy families and major corporations have used this strategy for over 100 years.

How much money do you need for infinite banking?

There is no universal starting premium or timetable for useful cash value. Review an actual illustration showing required and optional premiums, guaranteed and non-guaranteed values, surrender charges, and available loans. Paid-up additions may help shape a whole life policy, subject to rider limits and MEC testing.

What are the risks of infinite banking?

Risks include limited early cash surrender value, ongoing premiums and charges, loan interest, reduced death benefits, and lapse. A lapse or surrender with debt can create taxable income. Non-guaranteed dividends and crediting terms can change. Compare guaranteed and non-guaranteed illustrations and a lower-funding scenario before deciding.

Is infinite banking illegal?

Cash value life insurance and policy loans are established insurance features. Cash value generally grows tax-deferred, and death benefits are generally received free of federal income tax, subject to exceptions. Loan tax treatment depends on MEC status and the policy remaining in force; lapse or surrender with debt can create taxable income.

What does an IUL 0% index-crediting floor protect?

An IUL links interest crediting to an index without directly investing policy value in that index. A 0% index-crediting floor limits negative indexed interest; it does not guarantee that net policy value stays level. Policy charges and loan interest still apply, and withdrawals reduce value. Caps, participation rates, and other contract terms limit credited interest. Review guaranteed and non-guaranteed illustrations under lower-crediting and loan scenarios; the floor does not eliminate retirement-income or lapse risk.

Is there a medical exam required?

Many of our carriers offer no-exam or simplified underwriting options. Some policies require a basic health questionnaire. We'll find the best path based on your health profile.

Why should I trust First Freedom Life?

We're independent (not captive to one carrier) and veteran-owned. We educate first and never pressure. If it's not the right fit, we'll tell you.
Official 2024 ACS context

A sourced planning snapshot for California

California statewide context includes 13,548,091 households, 9,191,176 family households, 6,158,371 residents age 65 or older, 30,494,912 civilian adults, 2,139,116 self-employed workers, and 5,097,604 owner-occupied units with a mortgage. These estimates organize planning questions; they do not determine a product, coverage amount, rate, eligibility, or recommendation.

Residents age 65 and older

6,158,371

± 16,360 margin of error

Households

13,548,091

± 17,724 margin of error

Family households

9,191,176

± 23,875 margin of error

Civilian residents age 18 and older

30,494,912

± 3,789 margin of error

Self-employed workers

2,139,116

± 12,610 margin of error

Owner-occupied units with a mortgage

5,097,604

± 23,877 margin of error

U.S. Census Bureau · 2024 ACS 5-year Detailed Tables · B01001, B11001, B21001, B24080, B25027 · California (0400000US06) · margins of error shown at 90% confidence. No local office, individual financial condition, product fit, or outcome is inferred.

Privacy Policy Terms of Service
© 2026 First Freedom Life. All rights reserved.
🛡️ Open Calendar ↓
💬 Text Us 📞 Call Now
📞 Call Now (786) 567-6889 💬 Text Us 🛡️ Calendar ↓