Mortgage Protection Quote
Start with the secure mortgage protection quote form so we can match the home, budget, and family-protection goal. If you want help immediately, call First Freedom Life.
🛡️ Start Secure Quote Form 📞 Call (786) 567-6889 💬 Text UsFast quote help for homeowners who want the mortgage protected.
How much of your housing payment could your household cover on one income? You can ask for a term life quote for the remaining loan balance, or a smaller benefit that gives your family time to decide whether to stay in the home.
Free. No obligation. Takes less than 2 minutes.
Life insurance and annuity comparison options. Looking for a company you don’t see? Ask us. Availability varies by state, product and eligibility.
Tell us how much you owe, how long you expect to keep the mortgage and who depends on your income. Our team can help you compare coverage amounts and terms.
Managing Partner
Retirement Income & Annuities
Infinite Banking Practitioner
U.S. Air Force veteran · NPN 19759681
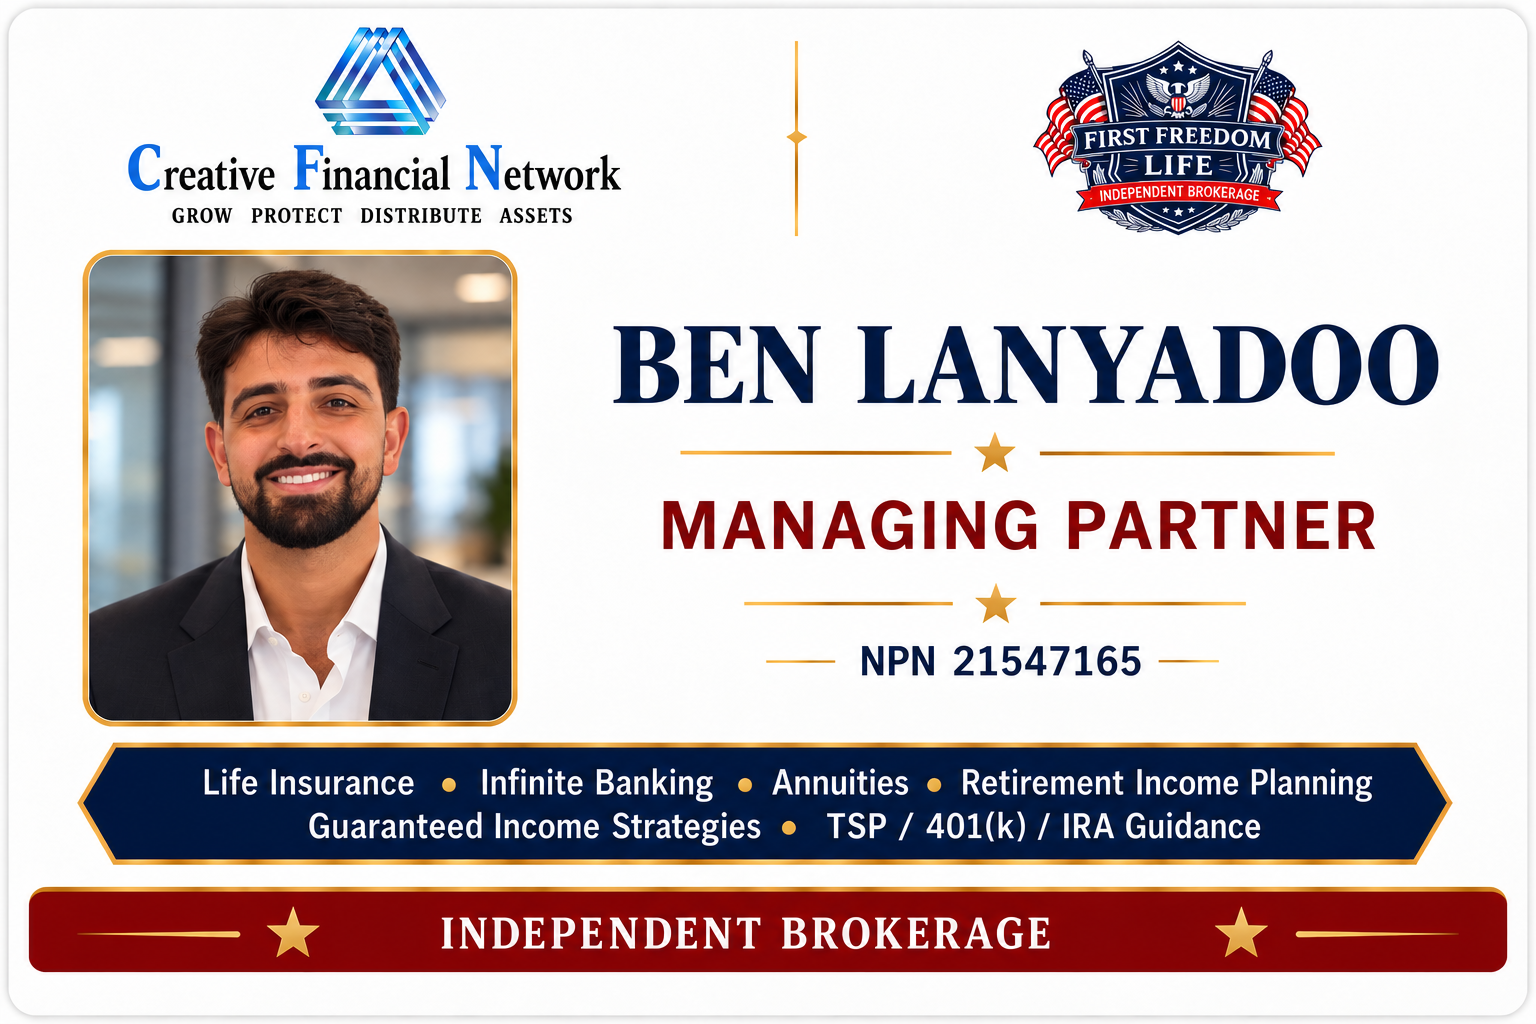
Managing Partner
Bachelor’s degree in Legal Studies, UC Berkeley
Retirement Income & Annuities · NPN 21547165
Managing Partner
Retirement Income & Annuities
Infinite Banking Practitioner · NPN 20292695
First Freedom Life is an independent, veteran-owned insurance brokerage. Coverage and premiums depend on the policy and the insurer’s underwriting.
Mortgage Protection Video
Short explainers focused on protecting the home and keeping the family protected if income disappears.
Verified California locality context
Protect the household behind the mortgage, not the lender or the house itself. The conversation begins with your goals and qualification details; no product or approach is treated as right for everyone.
California Department of Insurance
California Department of Insurance is the insurance-regulator identity listed by the NAIC for California. Its current consumer resources should be used to verify producer licensing, complaint guidance, approved forms, replacements, disclosures, and other state requirements before relying on a summary. Product availability and requirements depend on current California rules and the issued policy.
First Freedom Life is a Florida-based, veteran-owned independent insurance brokerage serving California statewide by phone and video. It does not maintain or claim an office in San Ramon and does not provide tax, legal, or investment advice.
Mortgage protection planning brief · San Ramon, California
A mortgage protection review is individualized by the current loan balance, remaining term, household income, co-borrower resources, other debts, existing coverage, health, budget, beneficiary plan, and whether level or decreasing protection fits the actual risk. The verified locality record identifies this San Ramon route without implying a local First Freedom Life office.
Official locality record for San Ramon, California
USGS GNIS identifies San Ramon in Contra Costa under feature ID 1656275. The 2024 Census Gazetteer independently lists San Ramon city under GEOID 0668378.
U.S. Census Bureau 2024 ACS five-year estimates with reported or derived margins of error. These figures describe the reviewed geography; they do not determine individual need, eligibility, suitability, or product choice.
California Department of Insurance
Verify the producer, insurer, approved forms, replacements, disclosures, and complaint guidance through the regulator identified by the NAIC for California (department ID 1029).
Mortgage protection is generally life insurance intended to address a housing-related need; it is not mortgage insurance and does not make First Freedom Life a lender or mortgage servicer.
With an individual term life policy, your named beneficiary receives the death benefit if you die while the policy is in force. They decide how much to put toward the home.
Suppose your household could cover everything except $2,000 of the monthly housing payment. Three years of that shortfall adds up to $72,000. Paying off the loan would call for a different amount. Include property taxes, insurance and any homeowners association dues when you work out the monthly figure.
Private mortgage insurance (PMI) protects the lender if a borrower defaults. Check your loan statement for a mortgage insurance charge. Separately, check whom you named on any existing life policy and what benefit they would receive. That can help you decide whether you need more life insurance.
A term life policy provides a death benefit. If an injury keeps you from working, a waiver-of-premium rider may cover the life insurance premium under its terms. Household mortgage payments are a separate expense. Some policies let you take part of the death benefit early for a qualifying illness, which reduces the amount available to beneficiaries.
Ask for the same coverage amount and term on each quote. Check how long the premium is guaranteed, what happens when that period ends, and which optional benefits add to the cost. Your final premium depends on the insurer’s underwriting decision.
Use the mortgage protection quote form to reach our team. For the conversation, have your approximate balance, years left on the loan and existing life coverage handy. Rough figures are enough to start.
Here we compare individual life insurance that a homeowner can use to provide for a surviving household. The named beneficiary receives the death benefit and can put it toward the loan, housing payments or other needs.
An individual quote depends on age, health, coverage amount and how long the policy will run. Ask for prices at two benefit amounts so you can see how each fits your monthly budget.
PMI protects the lender against borrower default. An individual life policy pays a death benefit to the beneficiary you name when a covered death occurs.
The insurer decides based on your application and its underwriting rules. Some applicants can use a process without an exam. Others may need an exam or additional medical information before receiving an offer.
A regular term life policy can serve this purpose. Choose an amount and duration based on how long someone would rely on your income to keep the home. Review any lender-linked offer separately to see who receives the benefit and whether it declines with the loan balance.