Retirement Income Review
Start with the secure review form or call now to compare income start dates, single or joint lifetime income, liquidity, beneficiary choices, and rollover fit.
Start Retirement Income Review 💬 Text Us 📞 Prefer to call? (786) 567-6889For people retiring now or soon with 401(k), 403(b), TSP, IRA, pension, CD, or savings money.
First Freedom Life · Veteran-Owned Independent Insurance Agency
Retiring now or soon with money in a 401(k), 403(b), TSP, IRA, pension, CD, or savings? Compare ways to turn an appropriate portion into dependable retirement income without giving up the liquidity your household still needs. Guarantees depend on the issuing insurer's claims-paying ability and the contract terms.
Free. No obligation. Takes less than 2 minutes.
Life insurance and annuity comparison options. Looking for a company you don’t see? Ask us. Availability varies by state, product and eligibility.
Jared + Erin · Founders & Owners
Work directly with the veteran-owned founders behind First Freedom Life for Annuity income guidance by phone and video nationwide.
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Retirement Income Video Guide
Short explainers on protected retirement money, income planning, index crediting, contract tradeoffs, and why liquidity and suitability come first.
Compare guaranteed retirement income options in Boca Raton for 401(k), IRA, pension, CD, and retirement savings. Review income start dates, liquidity, and rollover fit.

Boca Raton, Florida · Local context for your goals
Exploring annuity options in Boca Raton? Start with the income you want, when you want it to begin and the money you want to keep accessible. Compare your options whether retirement is years away or already here.
One local example—not a requirement to work with us
Example context: Households served by City of Boca Raton Utility Services; confirm the service address and account class
The City's residential water bill combines customer, capacity, and usage charges, and service outside City limits is priced differently.
Planning example, not a client case: If this utility serves your address, a minimum-use estimate may understate the recurring water and sewer budget.
What realistic monthly range should dependable retirement income cover while liquid reserves remain available?
Different situation? We will use your own budget, existing coverage and goals. Approximate figures are enough to start. Do not send account numbers, Social Security numbers or full statements by text.
Boca Raton Municipal Facilities and Services User Fee Schedule · reviewed 2026-09-05
https://www.myboca.us/1244/User-Fee-Schedule
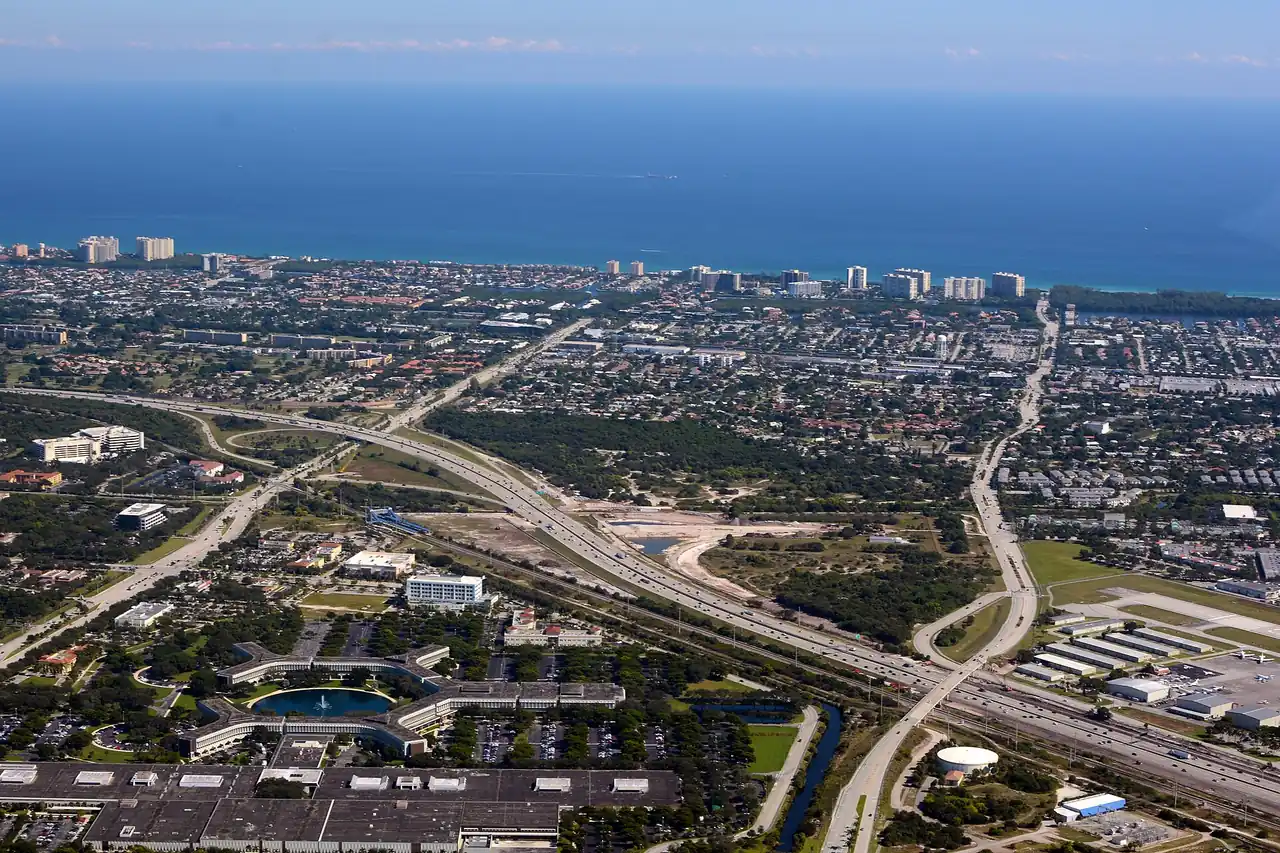
Photo: Aerial view over North Boca Raton in 2014. · Don Ramey Logan · CC BY-SA 4.0
Original source: https://commons.wikimedia.org/wiki/File:North_Boca_Raton_Florida_Aerial_photo_Don_Ramey_Logan.jpg
License: https://creativecommons.org/licenses/by-sa/4.0
Resized and re-encoded; the responsive display crops the photograph. The photograph shows a local scene, not a First Freedom Life office or an endorsement.
Confirm current terms and your actual address or account before using this information. Residence alone does not establish eligibility for a local program or an insurance product. First Freedom Life is an independent brokerage, not a local government or utility.
A local expense does not establish a need for an annuity. Guarantees depend on the issuing insurer; surrender terms, inflation, liquidity and single- versus joint-life terms matter. Existing income and savings may already meet the need.
Renters and homeowners are welcome. Owning property is not a requirement.
Start with the household income that would remain after either spouse dies, not just the payment available while both are living. Compare single-life and joint-life options using the same funding amount and start date. The survivor percentage, payment conditions and insurer guarantee should be clear in the actual proposal.
It depends on the contract and payout option. A life-only income election, a refund feature and an income rider can produce different outcomes. Ask to see what beneficiaries receive before income starts and after it starts. Do not assume a displayed income benefit base is cash your family can withdraw.
Bring your income target, start date and one-life or two-life income needs. Please do not send account numbers or sensitive documents by text.
Before signing, verify the agent's Florida license and the insurer's authority with Florida DFS. These checks apply statewide; there is no separate Boca Raton insurance approval implied here.
When an annuity replacement is proposed, Florida rules call for attention to surrender charges, a new surrender period, lost benefits and increased fees. Compare the existing contract as well as the new one.
Sources reviewed September 5, 2026:
Florida DFS — Verify Before You Buy
https://www.myfloridacfo.com/division/consumers/purchasingInsurance
Florida Statutes §627.4554 — Annuity recommendations
https://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0600-0699/0627/Sections/0627.4554.html
NAIC — Buyer’s Guide to Fixed Deferred Annuities (2022)
https://content.naic.org/sites/default/files/publication-anb-lp-consumer-annuities-fixed.pdf
Nationwide Peak 10 — one contract-specific example of an income benefit base that is not cash value; other contracts differ
https://www.nationwide.com/personal/investing/annuities/fixed-indexed/types/nationwide-peak-10
General education, not a personalized recommendation or tax or legal advice. Product terms, eligibility and the issuing insurer's claims-paying ability matter.

Verified Florida locality context
Plan how much retirement money should produce dependable income and how much should remain liquid. The conversation begins with your goals and qualification details; no product or approach is treated as right for everyone.
Florida Department of Financial Services resources support producer-license verification and consumer assistance. The Florida Office of Insurance Regulation oversees insurers and insurance forms. Product availability and requirements depend on current Florida rules and the issued contract. Florida Statutes section 627.4554 addresses duties for annuity recommendations; the actual transaction and current law control.
2024 ACS planning context
The ACS estimates 24,623 residents age 65 or older, 41,450 households, and 83,880 civilian adults in Boca Raton. Population data cannot determine an income plan. A guaranteed-income review starts with the actual income gap, desired start date, single- or joint-life need, liquidity, beneficiary provisions, inflation concerns, existing assets, and insurer strength.
24,623
± 1,319 margin of error
41,450
± 1,058 margin of error
83,880
± 1,181 margin of error
U.S. Census Bureau · 2024 ACS 5-year Detailed Tables · B01001, B11001, B21001 · Boca Raton city (1600000US1207300) · margins of error shown at 90% confidence. Estimates describe the Census geography, not an individual household, policy outcome, rate, eligibility decision, or First Freedom Life office.
A dependable-income plan must define the actual income gap, start date, single- or joint-life need, liquidity held outside the contract, surrender limits, beneficiary choices, inflation concerns, rider costs, and the issuing insurer’s claims-paying ability. Local demographic context never determines suitability or promises an outcome.
First Freedom Life is a Florida-based, veteran-owned independent insurance brokerage. It does not provide tax, legal, or investment advice.
A retirement-income review is for a specific need, not a generic product pitch. It is for a person retiring now or soon who has accumulated money but needs to understand how bills will be paid after employment income stops. Start with essential monthly expenses, subtract dependable sources such as Social Security and pensions, and identify the remaining income gap. Only then should you compare whether an annuity belongs in the plan.
A single-premium immediate annuity can begin payments soon. A deferred income annuity can start later. A fixed or fixed indexed annuity may offer an optional income rider. These structures solve different timing, liquidity, survivor, and legacy problems. The useful comparison is not simply FIA versus MYGA; it is income start date, amount, duration, access, cost, beneficiary treatment, and insurer strength.
When retirement money is eligible to move, a direct rollover or trustee-to-trustee transfer generally sends it from one qualified custodian to another without paying it to you first. That distinction matters because a payment made to you may trigger withholding and time-sensitive rollover rules. First Freedom Life can help coordinate the insurance side, while the plan administrator and tax professional confirm account-specific requirements.
Dependable income should not require locking up the money needed for emergencies, near-term purchases, health care, or family needs. Before recommending a contract, separate immediate cash reserves from long-term income assets, then review free-withdrawal provisions, surrender schedules, market value adjustments, rider charges, and death-benefit terms.
A higher single-life payment may stop at death. A joint-life option may continue for a spouse. Period-certain, cash-refund, or installment-refund provisions can change both the payment and what beneficiaries receive. The correct choice is a household decision, not a headline rate.
First Freedom Life is a veteran-owned independent insurance brokerage. We compare suitable annuity structures from multiple insurers and explain the tradeoffs in plain English. We do not promise that every person should move an account, and we do not present insurance guarantees as bank or government guarantees. The goal is to determine whether a defined portion of retirement savings can responsibly cover a real income gap.
Florida retirement-income planning
First Freedom Life's owner lives in Boca Raton. Boca-area households can begin by phone, and qualified South Florida cases may request an in-person follow-up when that would improve the retirement-income review.
Florida reviews are fact-specific. A page for Boca Raton does not create an office claim, an automatic recommendation, or a promise that an annuity will fit every household.
Prepare for a focused review
Boca Raton households receive the same focused retirement-income review available nationwide, plus a Florida-specific suitability planning layer on this page. Prepare these details so the conversation begins with your household's actual timing, accounts, liquidity, and income need.
An eligible retirement account may be transferred or directly rolled over into an annuity when the contract is suitable. A direct rollover or trustee-to-trustee transfer can avoid the mandatory withholding that may apply when a distribution is paid to you. Tax treatment depends on the account and transaction, so coordinate with your tax professional and plan administrator.
Immediate income annuities, deferred income annuities, and some fixed or fixed indexed annuities with income riders can create contractually defined income. The right structure depends on when income begins, whether it covers one or two lives, access to principal, beneficiary provisions, fees, surrender terms, and insurer strength.
No. A retirement-income plan can use only the portion appropriate for dependable income while leaving other money liquid or invested. The correct amount depends on essential expenses, Social Security, pensions, emergency reserves, health costs, legacy goals, and risk tolerance.
An annuity is an insurance contract, not a bank deposit, and it is not FDIC insured. Contract guarantees depend on the issuing insurance company's claims-paying ability and the specific terms of the contract.
Compare the income start date, payout amount and duration, single-life or joint-life coverage, inflation options, liquidity, surrender period, market value adjustment if any, rider fees, beneficiary or refund provisions, insurer financial strength, and the opportunity cost of moving the money.
It may not fit someone who needs full access to every dollar, lacks an emergency reserve, does not understand surrender restrictions, has a shorter time horizon than the contract, or already has enough dependable income. Suitability and product availability vary.