Infinite Banking Review
Use the embedded calendar or call now to discuss whether cash-value policy design can support your liquidity and family-bank goals.
📞 Call Now: (786) 567-6889 💬 Text UsA licensed agent can explain where infinite banking fits — and where it does not.
Infinite banking in Fort Lauderdale is a policy-liquidity strategy built around permanent life insurance. Review policy design, funding capacity, loan interest, repayment discipline, and alternatives before deciding whether it fits.
Free. No obligation. Takes less than 2 minutes.
Jared + Erin · Founders & Owners
Work directly with the veteran-owned founders behind First Freedom Life for Infinite Banking guidance by phone and video nationwide.
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Infinite Banking Video Guides
Short explainers on whole life policy loans, collateralized access, repayment flexibility, and the design risks that matter before using the Infinite Banking Concept.

Fort Lauderdale, Florida · Local context for your goals
Exploring Infinite Banking in Fort Lauderdale? Start with your goals, whether they involve family protection, future purchases or business cash flow. Compare a whole-life strategy with your existing savings, dependable surplus and accessible reserves.
One local example—not a requirement to work with us
Example context: Residential customers served by City of Fort Lauderdale utilities; verify meter, service location, and current rate schedule
Fort Lauderdale's residential water and wastewater bills use fixed and commodity charges, with costs varying by use and service location.
Planning example, not a client case: If City utilities serve your home, both fixed and usage charges compete with long-term policy funding.
Does premium capacity remain dependable after actual bills, possible higher use, and reserves?
Different situation? We will use your own budget, existing coverage and goals. Approximate figures are enough to start. Do not send account numbers, Social Security numbers or full statements by text.
New Utility Rates · reviewed 2026-09-05
https://www.fortlauderdale.gov/Government/Departments/Finance/Utility-Billing-and-Collections/New-Utility-Rates
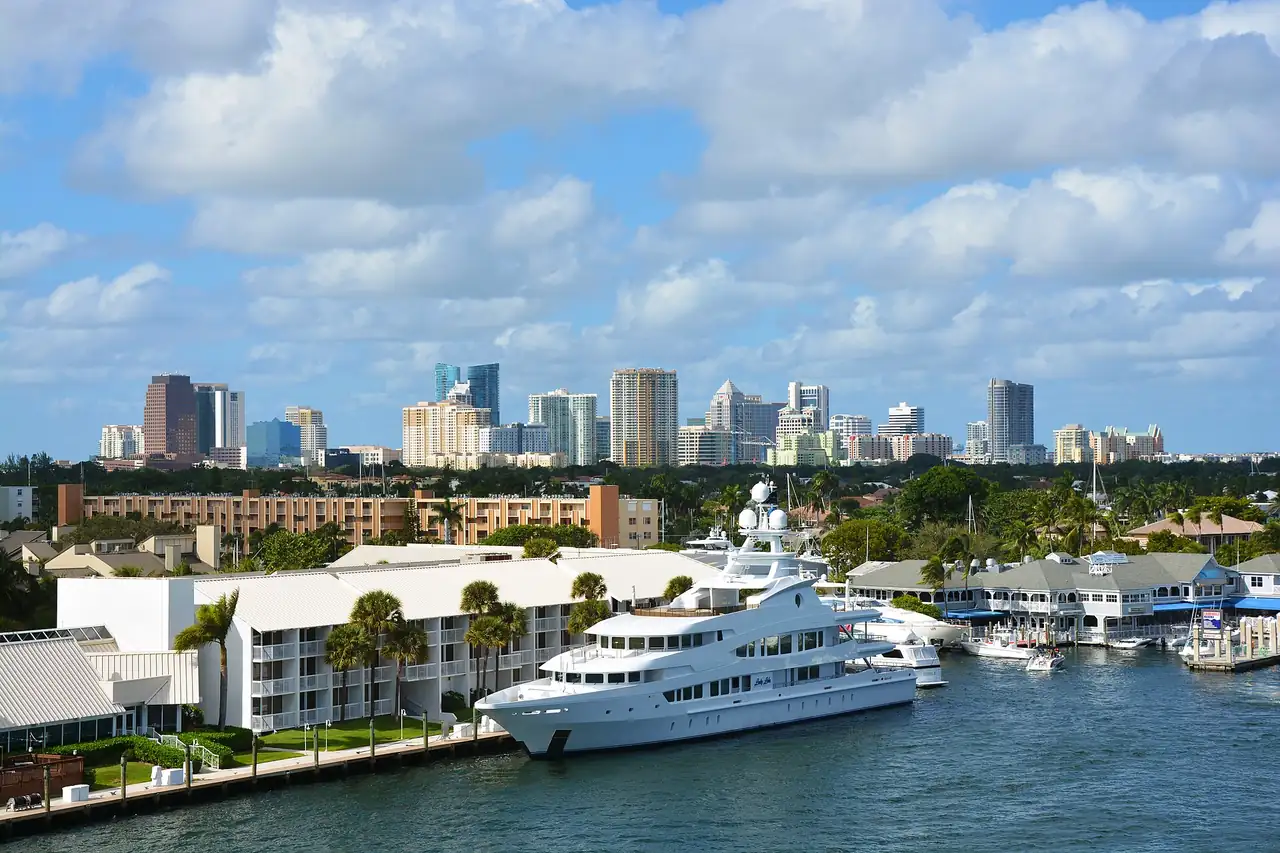
Photo: Downtown Fort Lauderdale skyline in 2015. · KeanoManu · CC BY-SA 4.0
Original source: https://commons.wikimedia.org/wiki/File:Skyline_of_Fort_Lauderdale,_Nov-15.jpg
License: https://creativecommons.org/licenses/by-sa/4.0
Resized and re-encoded; the responsive display crops the photograph. The photograph shows a local scene, not a First Freedom Life office or an endorsement.
Confirm current terms and your actual address or account before using this information. Residence alone does not establish eligibility for a local program or an insurance product. First Freedom Life is an independent brokerage, not a local government or utility.
Infinite Banking is a strategy using properly designed whole life insurance, not a bank account or an IUL policy. Premiums, limited early cash values, loan interest and lapse risk matter. Keeping money in ordinary savings may be the better fit.
Renters and homeowners are welcome. Owning property is not a requirement.
Often they describe different policy types or leave out the funding and loan assumptions. Bring the actual illustration, not just the marketing name. Compare guaranteed cash values, premiums, nonguaranteed assumptions and loan costs side by side. An IUL illustration is not interchangeable with the whole-life strategy discussed on this page.
Yes. Whether your income comes from wages, commissions or self-employment, keep household reserves separate from long-term policy funding. Test the required premium against a slower year, not just a strong month. Before purchasing, ask what reducing optional funding or missing a required payment would do to that specific policy.
Bring your budget, purchase timeline and any policy illustration to your call. Please do not send account numbers or sensitive documents by text.
Before signing, verify the agent's Florida license and the insurer's authority with Florida DFS. These checks apply statewide; there is no separate Fort Lauderdale insurance approval implied here.
Ask to see guaranteed policy values separately from nonguaranteed assumptions. Dividends are not guaranteed. Florida life-insurance solicitation rules address these disclosures; the policy, not a strategy label, determines your benefits.
Sources reviewed September 5, 2026:
Florida DFS — Verify Before You Buy
https://www.myfloridacfo.com/division/consumers/purchasingInsurance
Florida Statutes §626.99 — Life Insurance Solicitation
https://www.leg.state.fl.us/statutes/index.cfm?App_mode=Display_Statute&URL=0600-0699/0626/Sections/0626.99.html
NAIC — Life Insurance Buyer’s Guide (2026)
https://content.naic.org/sites/default/files/publication-lig-lp-consumer-life.pdf
Guardian — Life insurance policy loans
https://www.guardianlife.com/life-insurance/loans
General education, not a personalized recommendation or tax or legal advice. Product terms, eligibility and the issuing insurer's claims-paying ability matter.
Verified Florida locality context
Review the cash-flow strategy around insurability, premium capacity, liquidity, and policy-loan discipline. The conversation begins with your goals and qualification details; no product or approach is treated as right for everyone.
Florida Department of Financial Services resources support producer-license verification and consumer assistance. The Florida Office of Insurance Regulation oversees insurers and insurance forms. Product availability and requirements depend on current Florida rules and the issued contract.
2024 ACS planning context
The ACS estimates 14,873 self-employed workers, 40,619 family households, and 23,553 owner-occupied homes with a mortgage in Fort Lauderdale. Those counts are context, not a strategy recommendation. An Infinite Banking review still requires insurability, permanent protection need, stable premium capacity, emergency reserves, early liquidity, loan interest, repayment discipline, MEC limits, and lapse risk.
14,873
± 1,129 margin of error
40,619
± 1,043 margin of error
23,553
± 1,070 margin of error
U.S. Census Bureau · 2024 ACS 5-year Detailed Tables · B24080, B11001, B25027 · Fort Lauderdale city (1600000US1224000) · margins of error shown at 90% confidence. Estimates describe the Census geography, not an individual household, policy outcome, rate, eligibility decision, or First Freedom Life office.
R. Nelson Nash developed the Infinite Banking Concept® and explained the process in Becoming Your Own Banker®. The official Nelson Nash Institute distinguishes the banking process from a standalone product: implementation generally uses a properly structured dividend-paying whole life policy, while policy loans come from the issuing insurer with policy value serving as collateral. A Fort Lauderdale review should therefore test premium durability, early liquidity, loan interest, repayment discipline, death-benefit effects, MEC limits, and lapse risk—not treat the phrase “be your own bank” as a guarantee.
First Freedom Life is not affiliated with or endorsed by the Nelson Nash Institute. Registered terms are used only to identify Nash’s educational framework.
First Freedom Life is a Florida-based, veteran-owned independent insurance brokerage. It does not provide tax, legal, or investment advice.
Infinite banking in Fort Lauderdale is a policy-liquidity strategy built around permanent life insurance. Review policy design, funding capacity, loan interest, repayment discipline, and alternatives before deciding whether it fits.
Policy-liquidity decision context
Fort Lauderdale is the largest municipality in Broward County. Infinite Banking is a funding strategy built around a cash-value life-insurance contract, not a separate product or free-money shortcut. Compare the death-benefit need, premium commitment, early cash value, guarantees, dividend assumptions, policy-loan interest, repayment discipline, MEC limits, and the opportunity cost versus keeping cash or using conventional financing. Unpaid loans and interest reduce available cash value and death benefits and can increase lapse or tax risk.
Sources: City of Fort Lauderdale, About Fort Lauderdale; Florida Department of Financial Services, Life Insurance Overview. Accessed August 13, 2026.
The Infinite Banking Concept (IBC) is an educational framework for using permanent life insurance with cash value as one possible source of funding. A policy is still insurance first: premiums, underwriting, policy charges, cash-value timing, and the death-benefit need all matter. Policy loans are collateralized advances from the carrier, and the available amount, interest rate, and terms come from the contract.
A policy loan can provide access to cash value without treating the advance as a standard withdrawal, but tax treatment depends on the policy remaining in force and other facts. Loan interest accrues under the contract. Unpaid loan balance and interest can reduce cash value and the death benefit, increase lapse risk, and create tax exposure if the policy terminates with a gain. Review an illustration and the carrier loan provisions before borrowing.
Many IBC discussions focus on participating whole life, but no single design is right for every household or business. Whole life contracts specify certain values, while dividends are not promised and can change. Early cash value may be lower than premiums, paid-up additions have costs and limits, and funding must remain affordable through changing income.
For a Fort Lauderdale household or business owner, compare policy liquidity with emergency savings, a bank or conventional loan, term insurance, other permanent-life designs, and investments suited to the goal. Consider time horizon, underwriting, premium commitment, opportunity cost, creditor rules in FL, and the risk of relying on a policy for money needed soon.
First Freedom Life can explain how a proposed policy is intended to work, which values are contractual, which are illustrated, how charges and loans affect outcomes, and which assumptions require monitoring. A policy-loan strategy does not promise a return and is not a substitute for individualized tax, legal, or investment advice. Product availability and suitability vary by person and carrier.
IBC is a strategy that uses permanent life insurance with cash value as one possible source of policy liquidity. It is not a separate insurance product, and it does not remove the need to evaluate premiums, charges, insurance protection, loan interest, and lapse risk.
A policy owner may request a loan if the contract permits it and sufficient cash value is available. The carrier sets the loan terms and interest, and approval, timing, and available amounts vary. Keep appropriate outside reserves and compare the policy loan with conventional financing before proceeding.
A policy loan is generally not treated as current income while a qualifying policy remains in force, but tax results are fact-specific. A lapse or surrender with loans outstanding can create taxable income, and a Modified Endowment Contract changes distribution rules. Confirm the details with a qualified tax professional.
No. Policy accounting and loan treatment vary by contract. Loan interest accrues, and unpaid balances can reduce available cash value and death benefits or increase lapse risk. Review the carrier illustration and loan provisions rather than assuming the policy values will continue as illustrated.
No. It may not fit someone who needs low-cost temporary protection, cannot sustain the premium, needs immediate access to all funds, or has a shorter time horizon. Compare term life, savings, conventional credit, investments, and other permanent coverage before choosing a design.