Infinite Banking Review
Have a property purchase in mind? Bring the amount you need at closing, the closing date and any existing whole life policy statement. Ask us to compare the cash available on that date with the cost of borrowing it.
📞 Call Now: (786) 567-6889 💬 Text UsA licensed agent can explain where infinite banking fits — and where it does not.
Infinite banking in Orlando is a policy-liquidity strategy built around permanent life insurance. Review policy design, funding capacity, loan interest, repayment discipline, and alternatives before deciding whether it fits.
Free. No obligation. Takes less than 2 minutes.
Life insurance and annuity comparison options. Looking for a company you don’t see? Ask us. Availability varies by state, product and eligibility.
Bring your current policy statement or a proposed illustration. We can walk through the guaranteed values, premiums and borrowing terms with you.

Managing Partner
Retirement Income & Annuities
Infinite Banking Practitioner
U.S. Air Force veteran · NPN 19759681

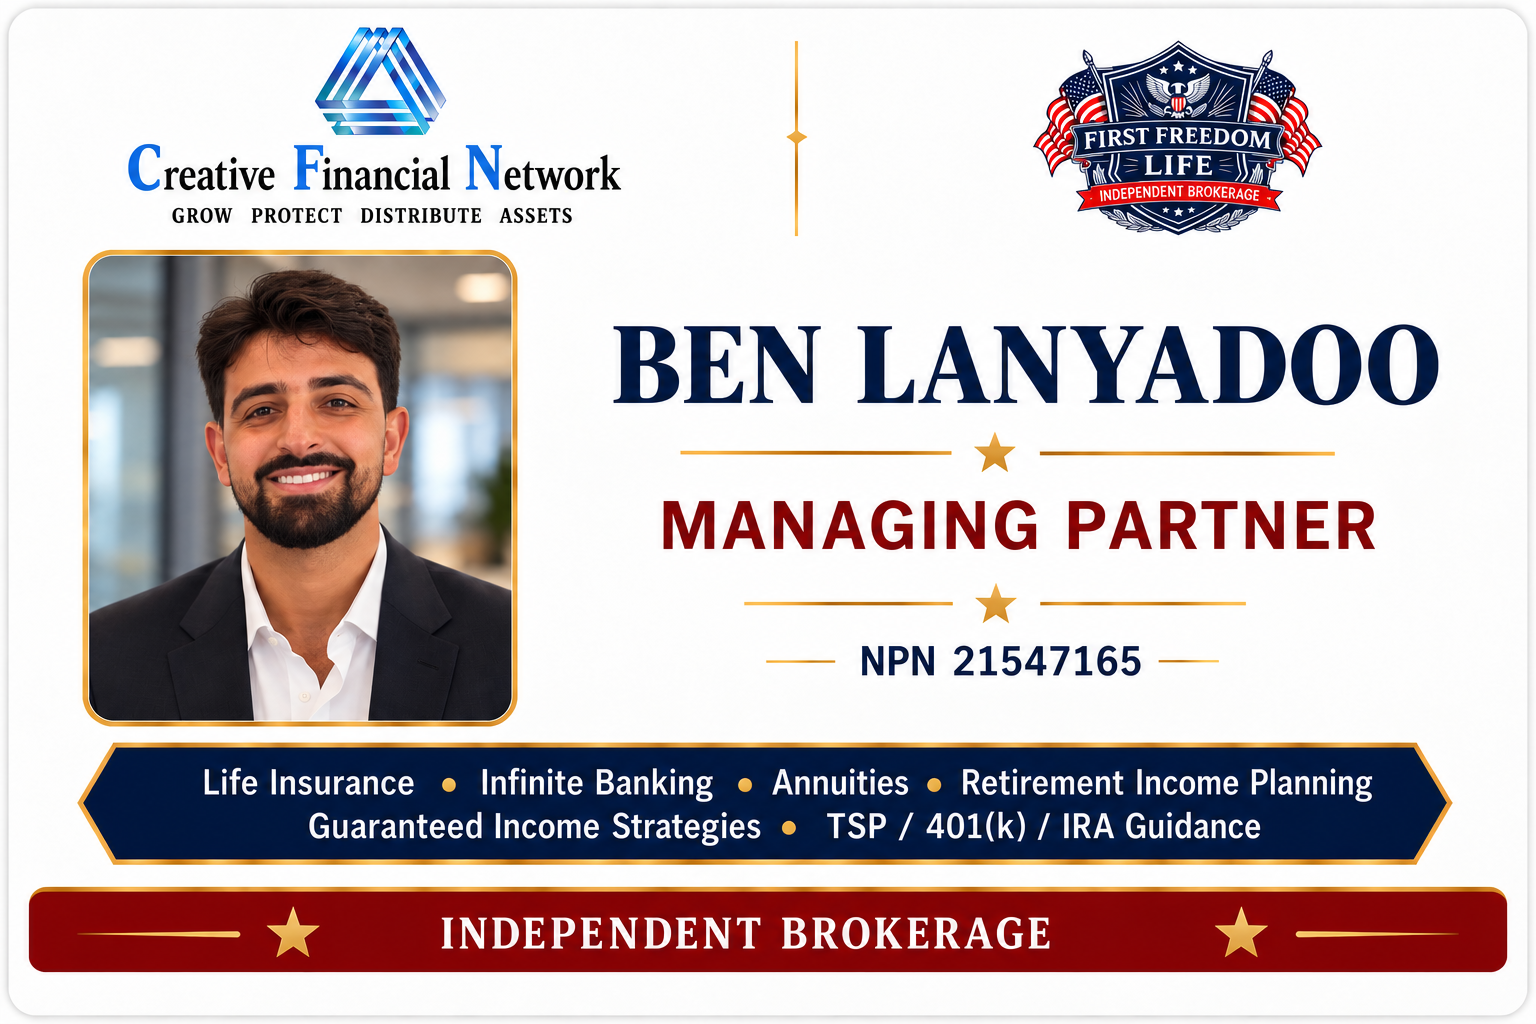
Managing Partner
Bachelor’s degree in Legal Studies, UC Berkeley
Retirement Income & Annuities · NPN 21547165

Managing Partner
Retirement Income & Annuities
Infinite Banking Practitioner · NPN 20292695
First Freedom Life is an independent, veteran-owned insurance brokerage. Life insurance guarantees depend on the issuing insurer’s claims-paying ability.
Infinite Banking Video Guides
Short explainers on whole life policy loans, collateralized access, repayment flexibility, and the design risks that matter before using the Infinite Banking Concept.
Verified Florida locality context
Review the cash-flow strategy around insurability, premium capacity, liquidity, and policy-loan discipline. The conversation begins with your goals and qualification details; no product or approach is treated as right for everyone.
Florida Department of Financial Services resources support producer-license verification and consumer assistance. The Florida Office of Insurance Regulation oversees insurers and insurance forms. Product availability and requirements depend on current Florida rules and the issued contract.
2024 ACS planning context
The ACS estimates 18,729 self-employed workers, 73,907 family households, and 34,792 owner-occupied homes with a mortgage in Orlando. Those counts are context, not a strategy recommendation. An Infinite Banking review still requires insurability, permanent protection need, stable premium capacity, emergency reserves, early liquidity, loan interest, repayment discipline, MEC limits, and lapse risk.
18,729
± 1,425 margin of error
73,907
± 1,680 margin of error
34,792
± 1,737 margin of error
U.S. Census Bureau · 2024 ACS 5-year Detailed Tables · B24080, B11001, B25027 · Orlando city (1600000US1253000) · margins of error shown at 90% confidence. Estimates describe the Census geography, not an individual household, policy outcome, rate, eligibility decision, or First Freedom Life office.
R. Nelson Nash developed the Infinite Banking Concept® and explained the process in Becoming Your Own Banker®. The official Nelson Nash Institute distinguishes the banking process from a standalone product: implementation generally uses a properly structured dividend-paying whole life policy, while policy loans come from the issuing insurer with policy value serving as collateral. A Orlando review should therefore test premium durability, early liquidity, loan interest, repayment discipline, death-benefit effects, MEC limits, and lapse risk—not treat the phrase “be your own bank” as a guarantee.
First Freedom Life is not affiliated with or endorsed by the Nelson Nash Institute. Registered terms are used only to identify Nash’s educational framework.
First Freedom Life is a Florida-based, veteran-owned independent insurance brokerage. It does not provide tax, legal, or investment advice.
Infinite banking in Orlando is a policy-liquidity strategy built around permanent life insurance. Review policy design, funding capacity, loan interest, repayment discipline, and alternatives before deciding whether it fits.
The Infinite Banking Concept (IBC) is an educational framework for using permanent life insurance with cash value as one possible source of funding. A policy is still insurance first: premiums, underwriting, policy charges, cash-value timing, and the death-benefit need all matter. Policy loans are collateralized advances from the carrier, and the available amount, interest rate, and terms come from the contract.
A policy loan can provide access to cash value without treating the advance as a standard withdrawal, but tax treatment depends on the policy remaining in force and other facts. Loan interest accrues under the contract. Unpaid loan balance and interest can reduce cash value and the death benefit, increase lapse risk, and create tax exposure if the policy terminates with a gain. Review an illustration and the carrier loan provisions before borrowing.
If you already own a policy, ask the insurer for the amount you can borrow today and an in-force illustration showing the proposed loan. If you are considering a new policy, ask what loan value is guaranteed by your closing date. Early cash value can be small. Compare the interest cost and the death benefit remaining with the loan outstanding.
For an Orlando property in Orange County, use the Orange County Property Appraiser’s Tax Estimator with the price you plan to pay. Add the estimated taxes, insurance and a repair reserve to your budget. If you take a policy loan for part of the purchase, check whether you can cover those bills, the policy premium and loan interest during a vacancy.
Suppose you need $30,000 in six months. Write down what you already have in savings, how much you want to keep for emergencies and how much you still need. Ask the insurer to show what happens if you borrow that balance and repay it over three years. Unpaid policy loans and interest reduce what beneficiaries receive. For a broader look at policy design, see our Florida Infinite Banking guide.
IBC is a strategy that uses permanent life insurance with cash value as one possible source of policy liquidity. It is not a separate insurance product, and it does not remove the need to evaluate premiums, charges, insurance protection, loan interest, and lapse risk.
A policy owner may request a loan if the contract permits it and sufficient cash value is available. The carrier sets the loan terms and interest, and approval, timing, and available amounts vary. Keep appropriate outside reserves and compare the policy loan with conventional financing before proceeding.
A policy loan is generally not treated as current income while a qualifying policy remains in force, but tax results are fact-specific. A lapse or surrender with loans outstanding can create taxable income, and a Modified Endowment Contract changes distribution rules. Confirm the details with a qualified tax professional.
No. Policy accounting and loan treatment vary by contract. Loan interest accrues, and unpaid balances can reduce available cash value and death benefits or increase lapse risk. Review the carrier illustration and loan provisions rather than assuming the policy values will continue as illustrated.
No. It may not fit someone who needs low-cost temporary protection, cannot sustain the premium, needs immediate access to all funds, or has a shorter time horizon. Compare term life, savings, conventional credit, investments, and other permanent coverage before choosing a design.