Mortgage Protection Insurance in Volusia County, FL
Mortgage Protection Quote
Protect the home while your family still has choices
Start with the secure mortgage protection quote form so we can match the home, budget, and family-protection goal. If you want help immediately, call First Freedom Life.
Fast quote help for homeowners who want the mortgage protected.
Use Secure Mortgage Quote Form →Start with the short secure form below. If a scheduling step appears after your details, choose the time that works best. Prefer to talk now? Use Call.
For homeowners in Volusia County, FL, mortgage protection is usually individually owned life insurance—not PMI. If the insured dies while the policy is in force and the claim is payable, the beneficiary generally receives the contract benefit and can decide whether to pay down the mortgage, keep payments current, or cover other household needs. Availability, underwriting, term length, riders, exclusions, and benefits vary by carrier and state.
🇺🇸 Veteran-Owned & OperatedClient ReviewsA.M. Best 'A' to 'A+' Rated Carriers
Free. No obligation. Takes less than 2 minutes.
★★★★★|
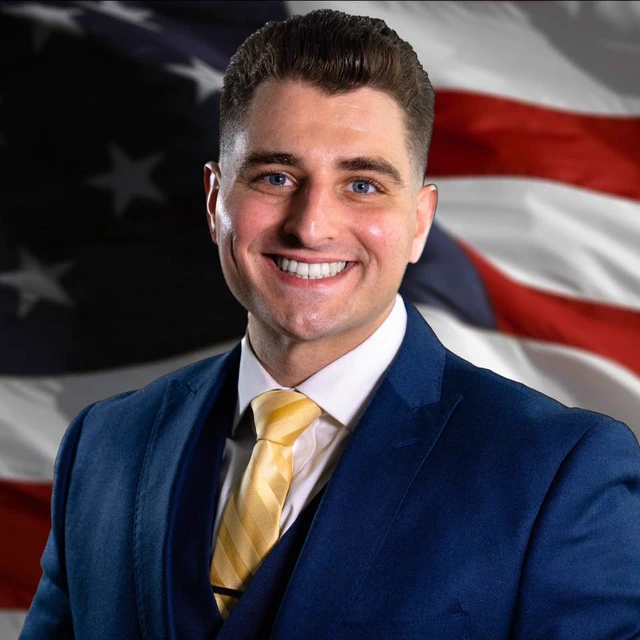
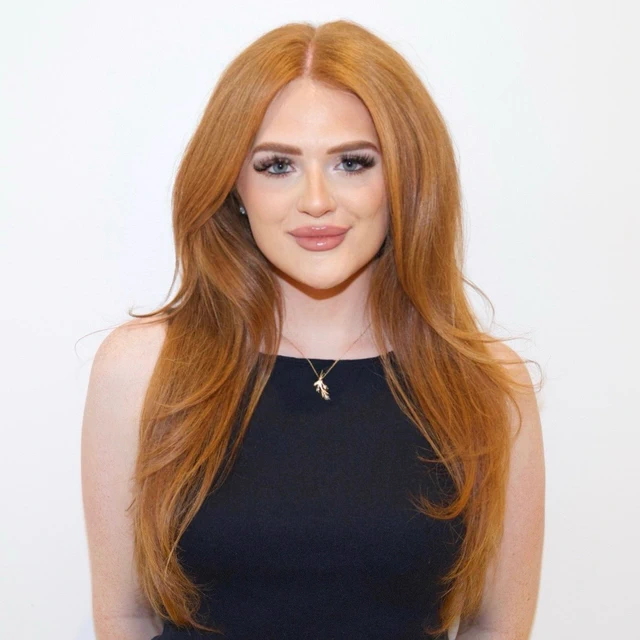
Jared + Erin · Founders & Owners
Meet Jared & Erin
Work directly with the veteran-owned founders behind First Freedom Life for Mortgage protection guidance by phone and video nationwide.
Co-Founder & Owner
Jared Aversano
U.S. Air Force veteran · Mortgage protection guidance · NPN 19759681
Co-Founder & Owner
Erin Bovee
Mortgage protection guidance · NPN 20292695
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Watch this firstMortgage Protection: Keeping the House ProtectedHow coverage can help a family stay in the home if income disappears after death or serious illness.
Mortgage Protection Video
Mortgage Protection Video Guide
Short explainers focused on protecting the home and keeping the family protected if income disappears.
Mortgage Protection vs. Regular Life InsuranceWhat to know before choosing coverage tied to a mortgage, family income, and living benefits.
Last Updated: July 2026
Quick Answer
Compare mortgage protection life insurance in Volusia County. Review death-benefit protection, underwriting, and available qualifying living-benefit riders. Short quote form. Veteran-owned.
What Happens to Your Volusia County Home If You Die Tomorrow?
A mortgage is often a household's largest monthly expense. If an insured homeowner dies, income may stop while the payment continues. Life insurance selected around the mortgage can provide beneficiary-controlled proceeds after a covered death while the policy is in force. Some policies also offer accelerated death-benefit riders after a qualifying illness, but rider definitions, limits, charges, and availability vary. The right amount and term depend on the balance, payment, income, savings, existing coverage, budget, and who would need to keep the home.
Why PMI Is Not the Same as Mortgage Protection
PMI generally protects the lender if the borrower defaults; it does not provide a life-insurance benefit to the family. Mortgage protection is individually owned life insurance. If the insured dies while the policy is in force and the claim is payable, the named beneficiary receives the contract benefit and decides whether to pay off the mortgage, keep payments current, cover living expenses, or use it for other needs. Life-insurance death benefits are generally income-tax-free under current federal law, with exceptions; individual tax treatment should be reviewed with a qualified tax professional.
What Can Mortgage Protection Include in Volusia County?
**Death Benefit** — A payable death benefit can give the named beneficiary funds that may be used for the mortgage or other household needs. The beneficiary controls the proceeds unless a different contractual arrangement applies.
**Living Benefits** — Some policies offer accelerated death-benefit riders after a qualifying terminal, chronic, or critical illness. Eligibility, definitions, benefit calculations, charges, and availability vary, and using a living benefit generally reduces the remaining death benefit.
**Disability-Related Features** — Some policies may offer waiver-of-premium or other disability-related riders. These features are not included in every policy and apply only when the rider's definitions and requirements are met.
Why Compare Mortgage Protection Through an Independent Broker
Carrier underwriting, available products, policy terms, rider definitions, and premiums can differ for the same homeowner. An independent broker can compare available options based on age, health, tobacco use, mortgage balance, desired term, family need, and budget. Compare the actual coverage, exclusions, rider terms, and a premium sustainable for your budget.
How to Request a Mortgage Protection Review in Volusia County
Call or text (786) 567-6889, or begin with the short secure form on this page.
1. Share basic information about the mortgage, age, health history, coverage goal, and budget.
2. A licensed agent reviews available carrier and underwriting options.
3. Compare the coverage period, benefit, premium, exclusions, riders, and policy requirements.
4. Decide whether an option fits; submitting the form does not obligate you to apply or buy.
First Freedom Life is a veteran-owned independent brokerage that compares available mortgage-protection options around your family's needs, budget, and underwriting profile.
Frequently Asked Questions
What is mortgage protection insurance in Volusia County?
Mortgage protection in Volusia County is usually individually owned life insurance selected around a homeowner's mortgage and family needs. If the insured dies while the policy is in force and the claim is payable, the named beneficiary receives the contract benefit and decides whether to pay down the mortgage, keep payments current, or cover other needs. Some policies offer accelerated death-benefit riders after a qualifying illness; terms and availability vary. Mortgage protection is not PMI.
How much does mortgage protection cost in Volusia County?
Premiums depend on age, health, tobacco use, coverage amount, term length, product design, state availability, and carrier underwriting. An independent review can compare available options for a Volusia County homeowner, but no particular rate, savings percentage, or approval outcome is guaranteed.
Is mortgage protection insurance the same as PMI?
No. PMI protects the lender if the borrower defaults. Mortgage protection is life insurance for the insured person's beneficiary. A payable death benefit is generally income-tax-free under current federal law, with exceptions, and the beneficiary decides how to use it. Available accelerated death-benefit or disability-related riders have qualifying events, definitions, limits, and charges that vary by policy.
Do I need a medical exam to get mortgage protection in Volusia County?
Some applicants may qualify for simplified or accelerated underwriting without a traditional medical exam. Exam requirements, eligibility, pricing, and approval timing depend on age, health history, prescriptions, coverage amount, state, and carrier rules. A no-exam path or approval within a particular time is not guaranteed.
How is mortgage protection different from regular life insurance?
Mortgage protection is not a separate universal policy type; it is often term or permanent life insurance selected around a mortgage balance, household budget, and protection period. The beneficiary generally controls a payable death benefit. Coverage does not automatically track the loan balance, and living-benefit, disability, or waiver features apply only when included and their contract requirements are met.