If you’re comparing plans for yourself or a parent, ask us to price the same benefit with each insurer. For example, we can compare $10,000 and $15,000 side by side and explain when each policy would pay the full amount.
Burial, cremation, and final-bill coverage questions answered by a licensed life insurance agent.
Use Secure Final Expense Form →Start with the short secure form below. If a scheduling step appears after your details, choose the time that works best. Prefer to talk now? Use Call.
Submit the short inquiry form first. Choosing a date and time afterward is optional; you do not need to book to request a review.
Loading your secure form…
Final expense insurance in Chicago is built for families who want burial, cremation, medical-bill, and end-of-life costs handled without leaving loved ones scrambling. As a veteran-owned independent broker, First Freedom Life helps you compare small whole-life and simplified-issue options from multiple carriers, then choose coverage only if it truly fits your family.
🇺🇸 Veteran-Owned & OperatedClient ReviewsA.M. Best 'A' to 'A+' Rated Carriers
Free. No obligation. Takes less than 2 minutes.
Veteran-owned. Independent. More options.
NationwideNorth AmericanAbilityAllianz LifeAmerican Century LifeAmerican EquityAmerican GulfAmerican LifeAmerican NationalAmericoAmeritasAspidaAtheneAtlantic Coast LifeAuguStarAxonicBaltimore LifeBrighthouse FinancialCL LifeCapitol LifeClear SpringCorebridge FinancialDelaware LifeELCO MutualEagle LifeEquiTrustEquitableF&GFarmers LifeGBU Financial LifeGlobal AtlanticGuaranty Income LifeGuardianHeartland NationalISDA LifeIbexisIntegrity LifeJacksonLiberty Bankers LifeLife of the SouthwestLincoln FinancialMassMutualMassMutual AscendMidland NationalMinnesota LifeMutual of OmahaNassauNational Western LifeNew York LifeOceanview LifeOneAmerica FinancialOxford LifePenn MutualPrincipalProtectiveReliance StandardRevol OneRiverSourceSBLISILACSagicorSecurian LifeSecurity BenefitSentinel Security LifeSymetraTalcott FinancialThe StandardThriventTransamericaTruStageUnited LifeWestern Catholic UnionWichita NationalNational Life GroupGerber Life
NationwideNorth AmericanAbilityAllianz LifeAmerican Century LifeAmerican EquityAmerican GulfAmerican LifeAmerican NationalAmericoAmeritasAspidaAtheneAtlantic Coast LifeAuguStarAxonicBaltimore LifeBrighthouse FinancialCL LifeCapitol LifeClear SpringCorebridge FinancialDelaware LifeELCO MutualEagle LifeEquiTrustEquitableF&GFarmers LifeGBU Financial LifeGlobal AtlanticGuaranty Income LifeGuardianHeartland NationalISDA LifeIbexisIntegrity LifeJacksonLiberty Bankers LifeLife of the SouthwestLincoln FinancialMassMutualMassMutual AscendMidland NationalMinnesota LifeMutual of OmahaNassauNational Western LifeNew York LifeOceanview LifeOneAmerica FinancialOxford LifePenn MutualPrincipalProtectiveReliance StandardRevol OneRiverSourceSBLISILACSagicorSecurian LifeSecurity BenefitSentinel Security LifeSymetraTalcott FinancialThe StandardThriventTransamericaTruStageUnited LifeWestern Catholic UnionWichita NationalNational Life GroupGerber Life
Life insurance and annuity comparison options. Looking for a company you don’t see? Ask us. Availability varies by state, product and eligibility.
★★★★★|
Meet your teamJared · Ben · Erin
Meet the team behind First Freedom Life. Get personal guidance comparing life insurance protection, living benefits and policy tradeoffs.
Jared Aversano
Managing Partner
Life Insurance
U.S. Air Force veteran · NPN 19759681
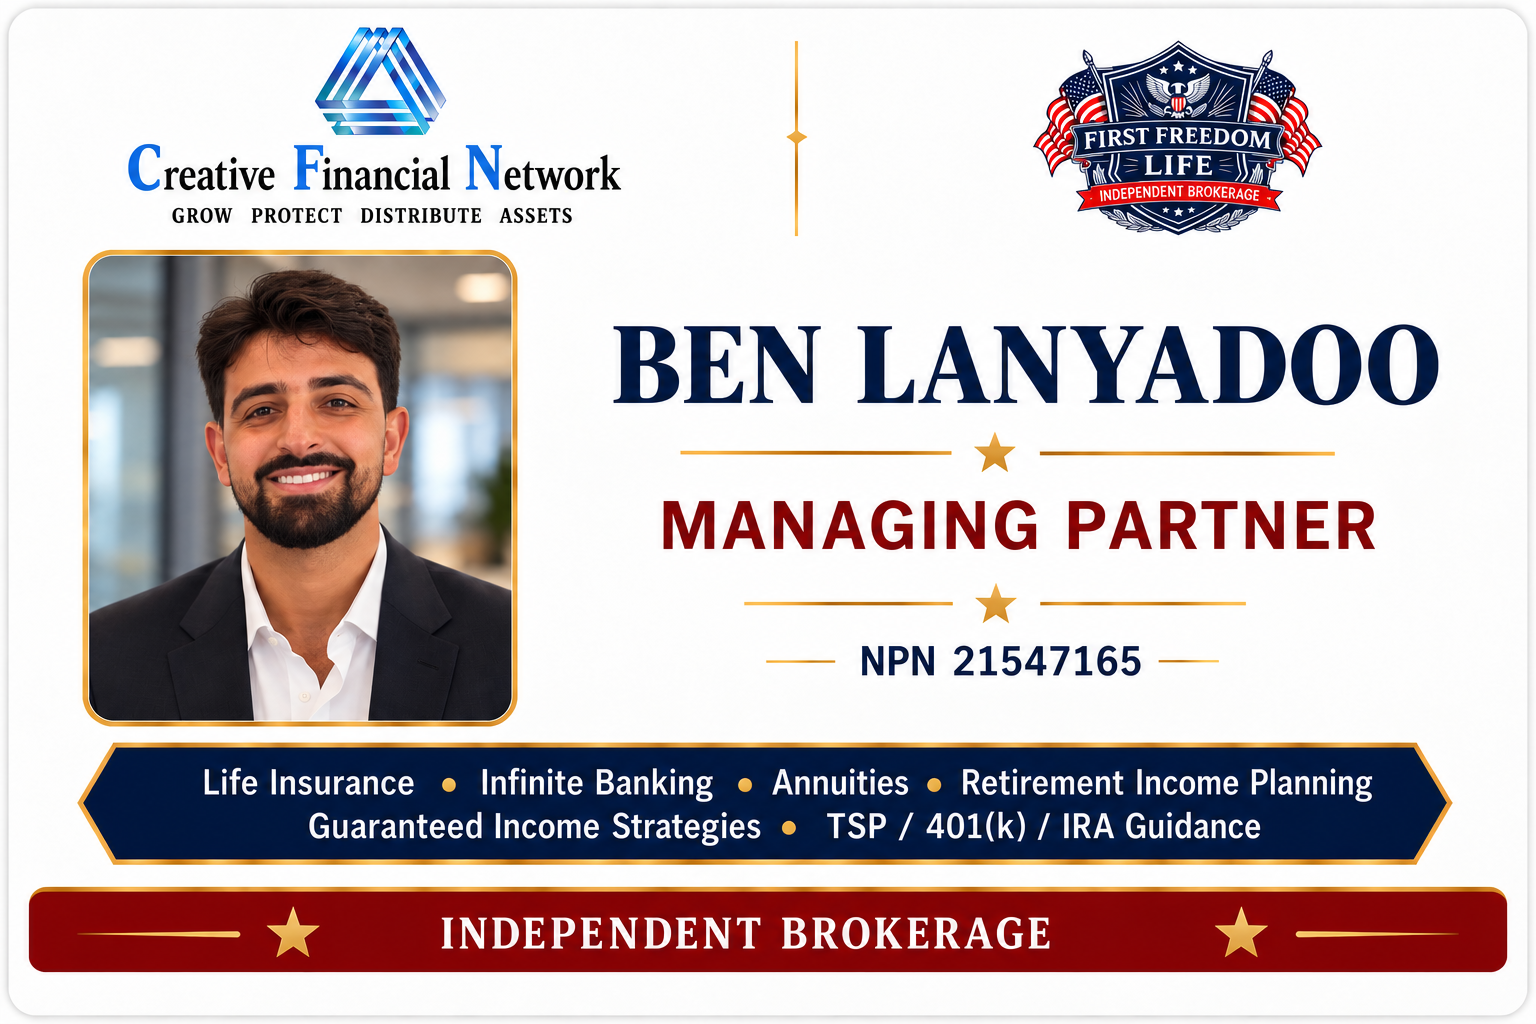
Ben Lanyadoo
Managing Partner
Bachelor’s degree in Legal Studies, UC Berkeley
Life Insurance · NPN 21547165
Erin Bovee
Managing Partner
Life Insurance
NPN 20292695
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Final Expense Planning
What to compare before choosing coverage in Chicago
Final expense coverage is generally smaller permanent life insurance intended to help with burial, cremation, and other final bills. Compare underwriting, waiting periods, benefit amounts, and a premium you can maintain.
Compare underwriting pathsSimplified-issue coverage asks health questions and may offer immediate full benefits when approved. Coverage issued without health questions may use graded benefits or waiting periods. Exact terms vary by policy.Choose a practical benefitEstimate funeral preferences, debts, and available savings, then select an amount that fits the need. The beneficiary generally controls how a payable death benefit is used, subject to the contract and applicable law.Keep the premium sustainableThe right policy is one you can keep in force. Compare premiums, guarantees, exclusions, and carrier underwriting instead of choosing coverage from a mailer or price alone.
Verified Illinois locality context
Final Expense Insurance decisions in Chicago, Illinois
Plan for funeral costs, final bills, and the beneficiary who will handle them. The conversation begins with your goals and qualification details; no product or approach is treated as right for everyone.
What is verified about this locality
USGS GNIS records Chicago as a populated place in Cook (feature ID 423587).
The U.S. Census Gazetteer lists Chicago city as a city (GEOID 1714000).
First Freedom Life serves Chicago remotely as part of its statewide Illinois service area. This page does not represent a local First Freedom Life office; meetings are offered by phone and video.
What this product review covers
Desired final-expense amount
Waiting-period and graded-benefit terms
Premium durability, issue age, and underwriting
Illinois insurance context
Illinois Department of Insurance
Illinois Department of Insurance is the insurance-regulator identity listed by the NAIC for Illinois. Its current consumer resources should be used to verify producer licensing, complaint guidance, approved forms, replacements, disclosures, and other state requirements before relying on a summary. Product availability and requirements depend on current Illinois rules and the issued policy.
USGS GNIS · 2026-07-01U.S. Census Gazetteer · 2024Illinois Department of Insurance · NAIC state insurance department directory · department ID 1038
First Freedom Life is a Florida-based, veteran-owned independent insurance brokerage serving Illinois statewide by phone and video. It does not maintain or claim an office in Chicago and does not provide tax, legal, or investment advice.
Final-expense coverage brief · Chicago, Illinois
Final-expense insurance decisions for Chicago
A final-expense review is individualized by the funeral and burial budget, remaining debts, family cash reserves, existing coverage, age, health, beneficiary plan, underwriting path, waiting periods, and an affordable premium.
How much should I ask for?
Start with the burial or cremation costs you want covered. Subtract savings you have already set aside and any existing insurance your family can use. Ask for a quote for the remaining amount and check whether the monthly premium fits your budget.
The USGS GNIS feature ID for Chicago is 423587. The 2024 Census Gazetteer lists Chicago city under GEOID 1714000.
Need, underwriting, and alternatives
Estimate funeral, burial or cremation, medical, debt, and immediate family cash needs without inflating the target.
Compare fully underwritten, simplified-issue, and graded-benefit designs, including any waiting or contestability period.
Review existing life insurance, savings, prepaid arrangements, beneficiaries, exclusions, and total premium cost.
Individual suitability checkpoint
Document the household objective, time horizon, existing resources, budget, and alternatives.
Compare state-approved carrier forms and the exact issued contract rather than relying on a generic city assumption.
Keep the calendar, beneficiary, liquidity, replacement, and tax questions tied to the individual facts.
2024 ACS place context for Chicago
Residents age 65 and older: 374,665 ±4,742
Households: 1,160,205 ±3,944
Population: 2,711,226 ±63
U.S. Census Bureau 2024 ACS five-year estimates with reported or derived margins of error. These figures describe the reviewed geography; they do not determine individual need, eligibility, suitability, or product choice.
Illinois verification
Illinois Department of Insurance
Verify the producer, insurer, approved forms, replacements, disclosures, and complaint guidance through the regulator identified by the NAIC for Illinois (department ID 1038).
Final-expense policies are life insurance. Benefits, waiting periods, exclusions, underwriting, premiums, and available amounts vary by insurer and the issued contract.
Last Updated: July 2026
Quick Answer
Compare burial insurance quotes in Chicago for $10,000 or $15,000 of coverage. Ask for the monthly premium, health questions and when the full benefit begins.
Why Final Expense Coverage Matters in Chicago
Final expense insurance is a small life insurance policy designed to help your family handle burial, cremation, funeral-home, medical-bill, and other end-of-life costs. It is not meant to replace a full income-protection plan or advanced cash-value strategy. It is meant to solve a very specific problem: when someone passes away, the family needs immediate money and clear instructions instead of stress, debt, or a rushed fundraiser.
The National Funeral Directors Association reported the national median cost of a funeral with viewing and burial at $8,300 in 2023, and the median cost of a funeral with cremation at $6,280. Costs vary by state, cemetery, funeral home, and family choices, but the point is simple: even a modest service can create a real bill. Final expense coverage gives families in Chicago a dedicated tax-free death benefit they can use when it is needed most.
What Final Expense Insurance Can Cover
Most final expense policies are permanent whole-life policies with smaller death benefits than traditional life insurance. Families often use the money for funeral services, cremation, burial plots, headstones, transportation, medical bills, credit cards, probate costs, or a small amount left behind for children or grandchildren.
The beneficiary is not usually forced to spend the money on a funeral. A properly structured life insurance death benefit is generally paid to the beneficiary, and the beneficiary decides how to use it. That flexibility matters because every Chicago family has a different situation: some need burial help, some need debt cleanup, and some simply want a small guaranteed legacy.
Simplified Issue vs Guaranteed Issue in Chicago
Final expense shoppers usually see two broad underwriting paths. Simplified-issue coverage asks a short set of health questions and usually does not require a medical exam. If you qualify, it can offer stronger value and faster full-benefit coverage than guaranteed issue.
Guaranteed-issue coverage typically asks no health questions, but it often costs more for the same benefit and may include a graded death-benefit period. That means the full benefit may not be available for natural death until the policy has been active for a set period. This is why it is important to compare options instead of buying the first mailer or TV offer you see.
How Much Final Expense Coverage Should a Chicago Family Consider?
Many families look at coverage amounts between $5,000 and $50,000, depending on funeral preferences, existing savings, debts, and whether they want to leave anything extra behind. The right amount is not always the maximum amount a carrier will approve. The right amount is the amount your family can comfortably keep in force.
A good final expense review should include your budget, health history, existing coverage, funeral preferences, and who would receive the benefit. Simplified-issue and no-health-question policies can differ in underwriting, premiums, waiting periods, and when the full death benefit becomes available. The practical goal is a benefit your family can use for final bills and a premium you can afford to keep in force.
Why Compare Carriers Before Buying
Final expense pricing and underwriting can vary dramatically by carrier. One company may decline or grade an applicant who another company can approve with immediate coverage. One mailer may look easy but be more expensive than an independent broker can find. That is why First Freedom Life compares options instead of pushing one company.
For Chicago families, the goal is not to be sold a policy. The goal is to understand whether final expense coverage, term life, whole life, mortgage protection, or another life insurance strategy fits your actual need. We keep the process simple: learn your goal, compare options, explain tradeoffs, and let you decide.
Frequently Asked Questions
What is final expense insurance in Chicago?
Final expense insurance in Chicago is a small life insurance policy designed to help pay burial, cremation, funeral, medical-bill, and end-of-life expenses. It is often structured as whole life insurance with a smaller death benefit and simplified underwriting.
Is final expense insurance the same as burial insurance?
Final expense insurance and burial insurance are often used to describe the same type of coverage. Both refer to smaller life insurance policies intended to help with funeral and end-of-life expenses. The benefit can usually be used for more than burial alone, including cremation, medical bills, debts, or family support.
Can I get final expense insurance with health problems?
Many people with health issues can still qualify for some type of final expense coverage. Simplified-issue policies ask health questions and may offer better value if you qualify. Guaranteed-issue policies may ask no health questions, but they can cost more and may include graded benefits. Comparing carriers matters.
Does final expense insurance require a medical exam?
Most final expense policies do not require a traditional medical exam. Many use simplified underwriting, prescription-history checks, and health questions. Exact requirements depend on the carrier, coverage amount, age, and health history.
How much final expense coverage do I need?
The right amount depends on funeral preferences, debts, savings, family support needs, and budget. Many families consider smaller benefits such as $5,000, $10,000, $15,000, $25,000, or more. The best policy is one your family can afford to keep active for the long term.
Should I buy final expense or term life insurance?
Final expense is usually best for burial and end-of-life bills. Term life is usually better for larger income-replacement or mortgage-protection needs. If your family still depends on your income or home payment, term or mortgage protection may be more appropriate. If your main concern is final bills, final expense may fit.