FIA: Protecting Retirement Money From Bad TimingHow a fixed indexed annuity can act as a protected bucket beside IRA, 401(k), CD, or savings money.
Annuity Payout Calculator for Monthly Income Planning
Request a personalized income comparison
Book below or call (786) 567-6889. Bring your planning amount, desired monthly income, funding source, income-start date, and single or joint preference. No transfer or product decision is required for the review.
Educational planning only; not a quote, carrier illustration, contract, recommendation, or tax or legal advice. Product availability, rates, benefits, riders, costs, and guarantees vary by carrier, contract, state, age, premium, payout option, and start date.
Monthly income target planning
Compare the retirement amount you are considering with the monthly income you want. The calculator shows the annual payout percentage that target would require—then a current carrier-approved illustration can determine what an actual contract may provide.
Jared + Erin · Founders & Owners
Meet Jared & Erin
Work directly with the veteran-owned founders behind First Freedom Life for Annuity income guidance by phone and video nationwide.
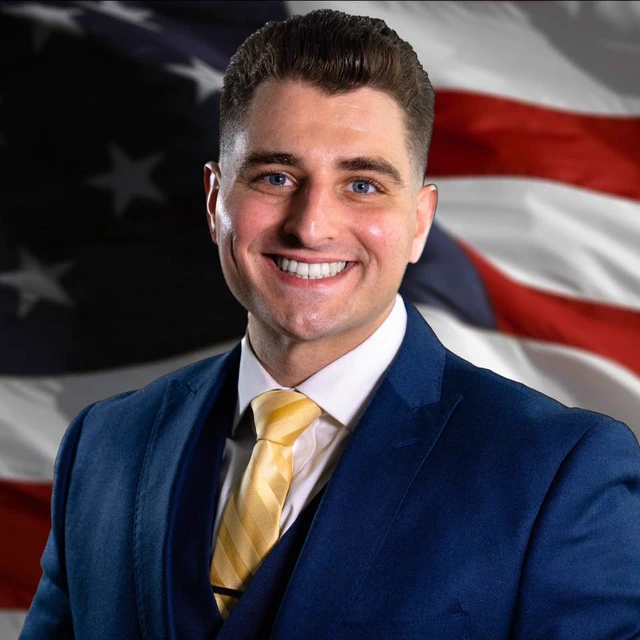
Jared Aversano
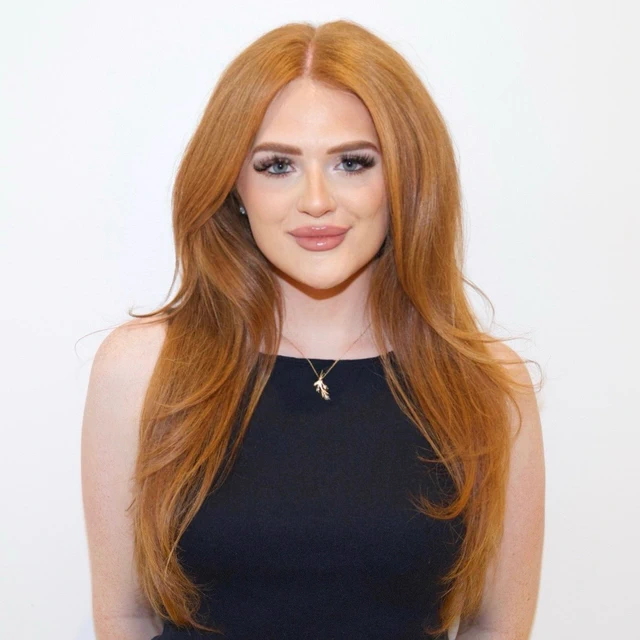
Erin Bovee
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Retirement Income Video Guides
Guaranteed Retirement Income Videos
Short explainers on protected retirement money, income planning, index crediting, contract tradeoffs, and why liquidity and suitability come first.
How FIA Index Crediting Actually WorksCaps, spreads, participation rates, and the tradeoff between principal protection and index-linked interest potential.
Check the math behind your monthly income target
Enter only planning amounts. Nothing typed into this calculator is transmitted, stored, or used to create a quote.
Actual annuity income depends on age, state, premium, income-start date, deferral period, single-life or joint-life selection, annuity type, rider, contract costs, liquidity provisions, survivor benefits, and issuing insurer. Product availability and terms vary. Guarantees are subject to the contract and the issuing insurer’s claims-paying ability.
What a real income comparison must include
A current carrier-approved illustration needs more than an account balance. Bring these details to compare available options without assuming every dollar should move.
- Your age and state of residence
- The amount being considered and where it is held: IRA, 401(k), TSP, pension, CD, or nonqualified savings
- When income should begin: now, within 12 months, or later
- Whether income should cover one life or continue for a spouse
- Liquidity, emergency reserves, beneficiary, and legacy priorities
- Any illustration or carrier product you already researched
Why two people with the same amount can receive different income
Age and start date
Income beginning now can differ from income deferred for one, three, or more years. Age and the exact start date affect carrier calculations.
Single or joint life
Income for one lifetime and income designed to continue for a spouse solve different needs and can produce different amounts.
Contract and rider
Immediate annuitization, deferred income, and optional income riders use different rules, costs, payout factors, and access provisions.
Liquidity and surrender terms
Free-withdrawal provisions, surrender periods, market-value adjustments, and emergency access can materially affect suitability.
Beneficiary choices
Life-only, period-certain, refund, and death-benefit features can change both income and what may remain for beneficiaries.
Insurer and state approval
Available carriers, products, riders, and contract terms vary by state. Every guarantee depends on the issuing insurer’s claims-paying ability.
Questions about annuity payout calculations
Does this calculator show what an annuity will pay?
No. It shows your monthly income target, annual income target, and the annual payout percentage your chosen amount would need to support. Actual annuity income requires a current carrier-approved illustration for your age, state, premium, start date, payout option, rider, and contract.
What changes an actual annuity income amount?
Age, state, premium, income-start date, deferral period, single-life or joint-life selection, annuity type, income rider, contract costs, liquidity provisions, survivor benefits, and the issuing insurer can all change available income.
Can retirement-plan money be used for an annuity?
Some eligible distributions from an IRA, 401(k), 403(b), TSP, solo 401(k), or pension may be transferred or directly rolled over when allowed and suitable. The plan administrator or custodian must confirm eligibility and instructions, and tax consequences should be reviewed with a qualified tax professional.
Do I have to use my entire retirement account?
No. Subject to plan rules, product minimums, distribution eligibility, and suitability, a partial allocation may be considered while other assets remain available for liquidity, growth, emergencies, or legacy goals.
What backs an annuity guarantee?
Annuity guarantees are obligations of the issuing insurance company and depend on its claims-paying ability and the contract terms. Annuities are not FDIC insured or bank guaranteed.
Where can I compare the broader decision?
Use the guaranteed retirement income guide to compare timing, liquidity, allocation, rollover logistics, and household needs before selecting a product.
Official educational sources
These government, regulator, and consumer-education materials informed the page. Their URLs are preserved in structured citation data while the visible source list keeps this review on First Freedom Life.
- NAIC — Buyer’s Guide for Deferred Annuities
- SEC Investor.gov — Annuity features, risks, costs, and guarantees
- FINRA Investor Education — Annuity income, expenses, surrender, and insurer considerations
- IRS — Rollovers of retirement plan and IRA distributions
- Florida Department of Financial Services — Annuity overview and consumer considerations
Rules, product approvals, and official guidance can change. Confirm current contract details with the issuing insurer and current plan requirements with the plan administrator or custodian. Consult qualified tax or legal professionals for advice within their scope.