Watch this first
FIA: Protecting Retirement Money From Bad Timing
How a fixed indexed annuity can act as a protected bucket beside IRA, 401(k), CD, or savings money.
Turn retirement savings into income you can plan around.
Book a guaranteed retirement income review
Use the calendar below or call (786) 567-6889. Bring the account type, approximate retirement date, desired income-start date, and any illustration you already researched. No transfer or product decision is required to have the conversation.
Annuities are long-term insurance contracts. Guarantees depend on the issuing insurer’s claims-paying ability. They are not FDIC insured or bank guaranteed. Surrender charges, market-value adjustments, withdrawal limits, rider terms, and tax consequences may apply. First Freedom Life does not provide tax, legal, or investment advice.
Guaranteed retirement income review
To purchase a guaranteed income annuity, start by comparing ways to create dependable retirement income from eligible 401(k), IRA, TSP, 403(b), solo 401(k), or pension assets—without assuming every dollar must move or that one annuity fits everyone.
- Income can be evaluated for retirement now or one to three years away
- Compare partial and full allocation strategies
- Review liquidity, contract terms, taxes, and insurer strength before deciding
Jared + Erin · Founders & Owners
Meet Jared & Erin
Work directly with the veteran-owned founders behind First Freedom Life for Annuity income guidance by phone and video nationwide.
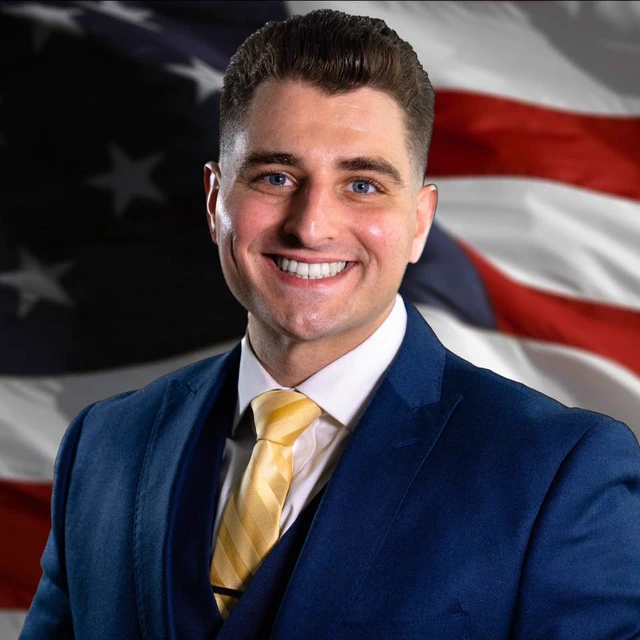
Jared Aversano
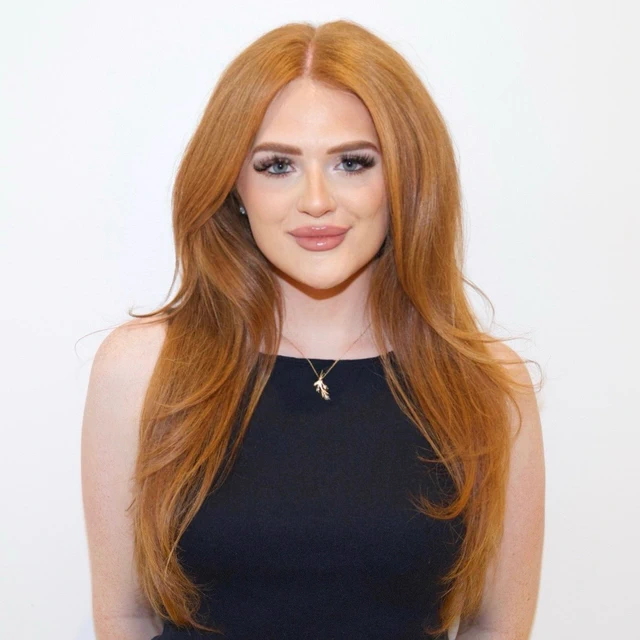
Erin Bovee
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Retirement Income & Annuity Video
Retirement Income & Annuity Video Guide
Short explainers on protected retirement money and fixed indexed annuity crediting. Lifetime-income options depend on the issuing insurer, contract terms, and elections.
How FIA Index Crediting Actually Works
Caps, spreads, participation rates, and the tradeoff between principal protection and index-linked interest potential.
How to purchase and compare an income annuity
An independent brokerage can help you evaluate an income goal and keep an appropriate liquidity reserve before requesting carrier quotes. The review can compare insurers and available contracts, then walk through income and beneficiary elections, suitability, the application, and any transfer or rollover steps. Rates, availability, and contract terms depend on the issuing insurer, state, and approved contract; insurer guarantees depend on claims-paying ability.
Monthly income planning tool
Check the math behind your retirement-income target
Use the annuity payout calculator to see the annual percentage your chosen retirement amount would need to support your desired monthly income. It is planning arithmetic—not a carrier quote or payout promise.
Income beginning soon
Compare the choices inside an immediate annuity
Use the immediate annuity (SPIA) guide when income should begin soon. Compare single or joint life, period-certain and refund choices, liquidity, taxes, inflation, and insurer strength before requesting an illustration.
Later-life longevity income
Planning for income at an advanced age?
Use the QLAC guide to understand the 2026 federal limit, RMD account-balance treatment, permitted funding sources, income-start deadline, liquidity restrictions, survivor choices, and insurer considerations.
Start with the decisions that change the answer
A meaningful review begins with the retirement outcome and the existing account—not a carrier name, teaser rate, or one-size-fits-all recommendation.
When should income begin?
Compare income that starts now with income designed to begin one, two, three, or more years later. The waiting period, age, and contract terms can materially change the available income.
One lifetime or two?
Single-life and joint-life income solve different household needs. A joint option may continue for a spouse, while a single-life option may produce a different income amount.
How much must stay accessible?
Emergency reserves, planned purchases, health expenses, and other goals belong outside money committed to surrender periods or limited withdrawal provisions.
Partial or full allocation?
You may not need to move an entire retirement account. Subject to plan rules, eligibility, minimums, and suitability, different dollars can keep different jobs.
Where is the money now?
Account type matters. A 401(k), IRA, TSP, 403(b), solo 401(k), pension, CD, and taxable account can have different transfer, tax, access, and administrative rules. If a pension offers a choice, compare the pension lump sum and lifetime-income tradeoffs before taking action.
What must the contract prove?
Review the carrier illustration and contract for income terms, surrender period, withdrawal provisions, death-benefit treatment, fees, rider terms, and insurer financial strength.
Build the income plan around the household
The right comparison separates income, liquidity, growth, and legacy instead of forcing every retirement dollar into the same solution.
1
Define the retirement paycheck gap
Estimate essential and flexible monthly spending, then subtract dependable income such as Social Security or a pension. The remaining gap is the amount the strategy needs to address.
Verify before acting
Inflation, survivor needs, taxes, health costs, and irregular expenses can make a simple monthly estimate incomplete.
2
Choose an income-start window
A household retiring now may need immediate income. Someone retiring in one to three years can compare a delayed start while keeping enough money available for the transition.
Verify before acting
Income figures are contract-specific. Use the carrier illustration for the exact age, premium, start date, income option, and state approval.
3
Assign each dollar a job
One portion may support lifetime income while other assets remain liquid, invested, or reserved for near-term needs. A partial allocation can be considered when permitted and suitable.
Verify before acting
Product minimums, plan distribution rules, required minimum distributions, surrender terms, and the rest of the household balance sheet matter.
4
Coordinate eligible transfer paperwork
First Freedom Life can help coordinate an insurance application and transfer or rollover paperwork after the plan administrator or custodian confirms distribution eligibility and instructions.
Clear boundary
First Freedom Life does not administer employer retirement plans. First Freedom Life does not provide tax or legal advice. Confirm current requirements with the plan administrator or custodian and a qualified tax professional before acting.
Questions clients ask before moving retirement money
Do I have to move the whole account?
No. A partial allocation may be considered when the plan permits it and the amount meets product and suitability requirements. Keeping liquid or invested assets outside the annuity may be important.
Can income start later?
Some contracts allow a later income start. The available income depends on the exact contract, premium, age, start date, income option, and state approval—not a generic online estimate.
Can existing retirement assets be used?
Possibly. Eligible distributions from a 401(k), IRA, TSP, 403(b), solo 401(k), or pension may sometimes move directly while preserving tax deferral. The current plan or custodian must confirm eligibility.
What about required minimum distributions?
RMD rules can affect timing and what is rollover-eligible. A required distribution generally cannot be rolled over. Confirm the current rule and amount with the plan, custodian, and qualified tax professional.
What if I already researched a product?
Bring the exact illustration or contract name. We can compare its income, liquidity, surrender terms, rider cost, death-benefit treatment, and assumptions without assuming it is automatically the best fit.
What makes the income guaranteed?
The contract may guarantee specified income when its conditions are met. Every guarantee is an obligation of the issuing insurer and depends on that insurer’s claims-paying ability.
How do I purchase a guaranteed income annuity?
An independent brokerage can help compare available insurers and contracts around your income goal and liquidity reserve. The review can include carrier illustrations, contract elections, suitability, the application, and transfer steps; rates, availability, and terms depend on the insurer, state, and approved contract.
Official educational sources
These government and investor-education materials informed this page. Their URLs are preserved in the structured citation data while the visible source list keeps this review captive on First Freedom Life.
- IRS — Rollovers of retirement plan and IRA distributions
- IRS — Required minimum distributions for retirement plans and IRAs
- U.S. Department of Labor — Questions to ask before a retirement-account rollover
- SEC Investor.gov — Annuity features, risks, costs, and guarantees
- Florida Department of Financial Services — Annuity overview and consumer considerations
Rules, plan provisions, product approvals, and official guidance can change. Confirm current requirements with the plan administrator or custodian, issuing insurer, and qualified tax or legal professional before taking action.