FIA: Protecting Retirement Money From Bad TimingHow a fixed indexed annuity can act as a protected bucket beside IRA, 401(k), CD, or savings money.
Immediate Annuities (SPIAs) for Income That Starts Soon
Request a Personalized SPIA Income Comparison
Book below or call (786) 567-6889. Bring the amount being considered, funding source, state, birth dates, preferred income-start date, and single or joint preference. No transfer or product decision is required for the review.
Educational comparison only; not a quote, illustration, recommendation, contract, tax advice, or legal advice. Income, options, availability, and terms vary by age, state, premium, start date, payout election, product, and insurer.
Income beginning soon
A single premium immediate annuity exchanges one premium for scheduled income that usually begins within one year. Before choosing one, compare whose lifetime is covered, what may remain for beneficiaries, how much liquidity is given up, and how inflation and taxes affect the household.
Jared + Erin · Founders & Owners
Meet Jared & Erin
Work directly with the veteran-owned founders behind First Freedom Life for Annuity income guidance by phone and video nationwide.
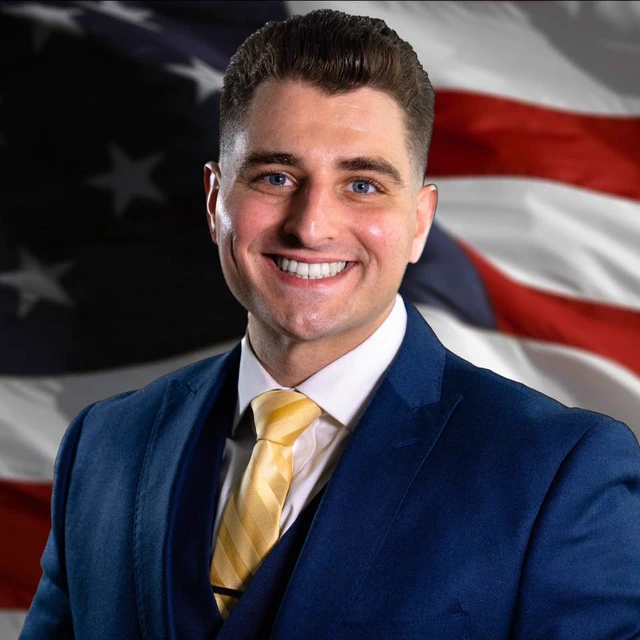
Jared Aversano
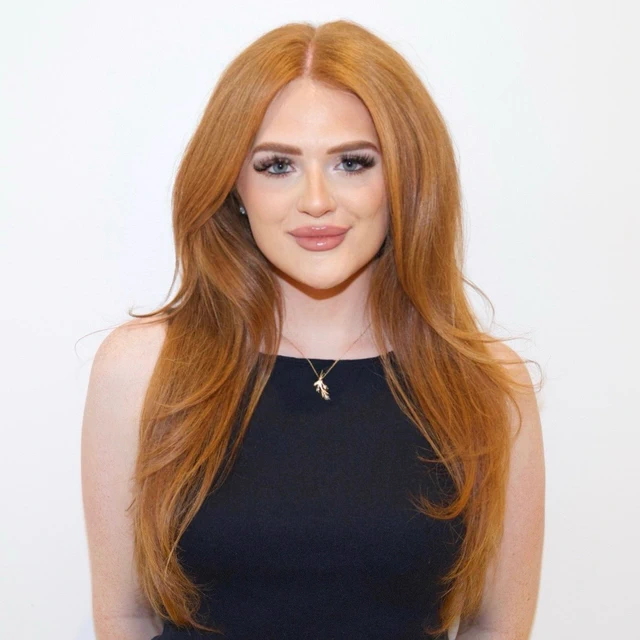
Erin Bovee
First Freedom Life is a veteran-owned independent insurance brokerage. Product availability, guarantees, costs, taxation, and suitability vary.
Retirement Income Video Guides
Guaranteed Retirement Income Videos
Short explainers on protected retirement money, income planning, index crediting, contract tradeoffs, and why liquidity and suitability come first.
How FIA Index Crediting Actually WorksCaps, spreads, participation rates, and the tradeoff between principal protection and index-linked interest potential.
The payout option changes the promise
The same premium can address different household goals. An election that protects a second life or beneficiary typically changes the scheduled income, and the choice normally becomes permanent when payments begin.
Life-only
Income is tied to one person’s lifetime and generally ends at that person’s death. It may prioritize income during life but can leave no continuing payment for a beneficiary.
Joint and survivor
Income is designed to continue under the selected contract terms while either of two covered people is alive. The survivor percentage and other terms must be confirmed before election.
Life with period certain
Lifetime income includes a minimum payment period. If death occurs during that period, remaining scheduled payments may continue to the named beneficiary under the contract.
Cash-refund option
If contract payments before death are less than the amount defined by the refund provision, a remaining amount may be paid to the beneficiary according to the contract.
Installment-refund option
A remaining contract-defined refund may continue through installments instead of one payment. Availability and mechanics vary by insurer, product, and state.
Fixed or increasing payments
A level payment may lose purchasing power. If an increasing or cost-of-living option is available, compare its lower starting income and exact adjustment terms.
What must be settled before income starts
A SPIA can transfer longevity risk to an insurer, but it also asks the household to make choices about access, legacy, inflation, and permanence.
- Keep emergency reserves and near-term spending outside money committed to income.
- Understand that annuitization is generally irrevocable and access to the premium is often limited or unavailable after payments begin.
- Compare early-death outcomes under life-only, period-certain, and refund choices.
- Decide whether one lifetime or two must be covered and what survivor percentage is needed.
- Stress-test level income for inflation and changing health, housing, and care costs.
- Review the issuing insurer because every contractual obligation depends on its claims-paying ability.
SPIA, deferred income, FIA, or MYGA?
These are different intent owners. The right comparison begins with when income is needed and whether the money must remain accessible or continue accumulating.
1
SPIA: income starts soon
One premium is exchanged for scheduled income that generally begins within one year. There is typically no accumulation phase, and annuitization is generally permanent.
2
Deferred income or an income rider: income starts later
These approaches use a future start date and different contract mechanics. A fixed indexed annuity with an income rider is not the same as a SPIA, and rider-based withdrawals are not the same as immediate annuitization.
3
FIA or MYGA: accumulation comes first
A fixed indexed annuity or multi-year guaranteed annuity is generally evaluated for accumulation, protection, or a later income decision. Neither label by itself answers what income beginning soon will provide.
4
Calculator or pension comparison: planning comes first
The income-target calculator checks planning arithmetic only. A pension election is a separate employer-plan decision. Neither substitutes for a current SPIA illustration and contract.
5
Replacement and conflicts: compare the full transaction
If an existing annuity or other financial product would be replaced, compare surrender costs, lost benefits, new restrictions, any applicable new contestability period, and all compensation or conflicts. A recommendation must address the consumer’s situation, needs, objectives, liquidity, tax status, time horizon, and existing products.
Funding source changes the tax conversation
Qualified retirement money
Payments funded entirely with pretax IRA or eligible employer-plan money are generally taxable as distributed. Transfer eligibility, required minimum distributions, withholding, and plan rules need separate review.
Nonqualified money
Payments from a contract purchased with after-tax funds may include both taxable earnings and recovery of basis. The taxable portion depends on federal tax rules and the specific contract.
Get case-specific guidance
First Freedom Life does not provide tax or legal advice. Confirm transfer instructions with the custodian or plan administrator and review the actual tax treatment with a qualified tax professional.
Suitability boundary: a SPIA may be unsuitable when the household needs access to the premium, lacks adequate reserves, has unresolved debt or care needs, cannot accept the elected beneficiary outcome, or has not compared available alternatives.
Immediate annuity questions
What is a single premium immediate annuity (SPIA)?
A SPIA is an insurance contract generally purchased with one premium in exchange for scheduled income that usually begins within one year. The contract, income option, start date, and issuing insurer determine the actual terms.
How soon can SPIA income begin?
Immediate-annuity income commonly starts soon after purchase and generally within one year. The exact first payment date and available payment frequency must be confirmed in the insurer-approved illustration and contract.
What is the difference between single-life and joint-and-survivor income?
Single-life income is tied to one person’s lifetime. Joint-and-survivor income is designed to continue under the selected contract terms while either of two covered people is alive. The election can change the income amount and generally cannot be changed after payments begin.
Can an immediate annuity leave money to beneficiaries?
It depends on the payout option. Life-only income may end at death, while period-certain or refund options may provide specified payments or value to a beneficiary. Adding beneficiary protection generally changes the income amount, so early-death and legacy priorities should be compared before election.
Can I withdraw the premium after SPIA payments begin?
Often, access is limited or unavailable after annuitization because the premium has been exchanged for the contract’s income obligation. The election is generally irrevocable, subject to the exact contract and any applicable free-look rights. Keep separate liquidity for emergencies and near-term needs.
How are immediate-annuity payments taxed?
Tax treatment depends on the funding source and the contract. Payments funded entirely with pretax qualified retirement money are generally taxable when distributed; payments from a nonqualified contract may include both taxable earnings and recovery of after-tax basis. Consult a qualified tax professional for the specific case.
Official educational sources
These regulator, government, and consumer-education materials informed this page. Their URLs are preserved in structured citation data while the visible source list keeps the review on First Freedom Life.
- SEC Investor.gov — Immediate and deferred annuity timing
- FINRA Investor Insights — Immediate-annuity income, legacy, inflation, and insurer considerations
- FINRA Investor Education — Annuity payout choices, liquidity, costs, and contract review
- IRS Publication 575 — Pension and annuity income tax treatment
- NAIC — Annuity consumer education and state insurance oversight
- Florida Department of Financial Services — Annuity options, replacement, suitability, compensation, and consumer questions
Annuity obligations depend on the issuing insurer’s claims-paying ability and the contract terms. Annuities are not FDIC or SIPC insured and are not bank deposits or bank guaranteed. Product approval and availability vary by state. Confirm current terms in the insurer-approved illustration and contract.